Marginal Revenue and Marginal Cost: Output, Price and Profit
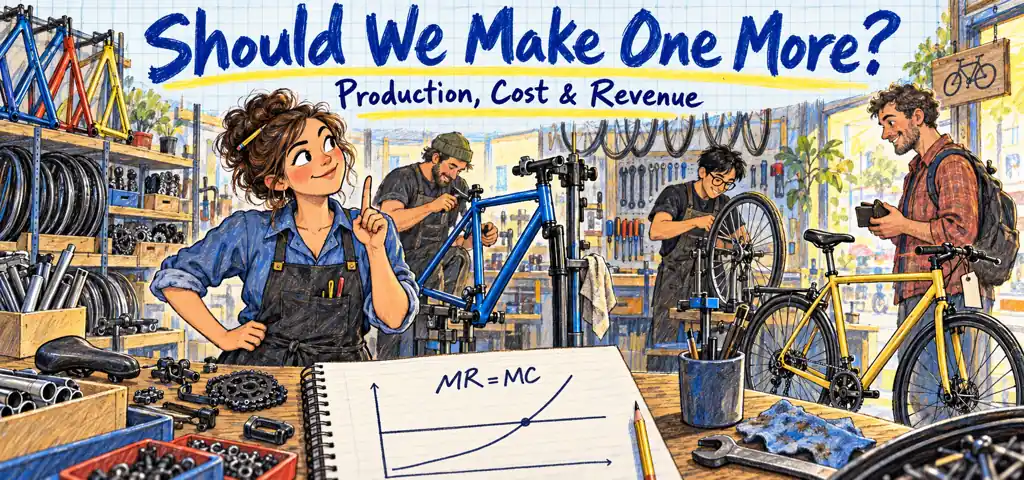
Marginal revenue and marginal cost help choose output; price and average total cost determine profit at that output. Keep those steps separate. In the usual smooth model, an interior profit maximum has MR = MC with the appropriate crossing, but you must also compare operating with shutting down. For the monopoly examples here, assume one price and downward-sloping demand.
The same marginal rule operates under different market structures.
Apply Three Production and Cost Checks
Which statement about the MR=MC rule is correct?
- It applies only to perfectly competitive firms.
- It guarantees positive economic profit.
- It identifies price directly for every market structure.
- It requires fixed cost to equal zero.
- It selects the profit-maximizing quantity under the usual conditions.
It selects the profit-maximizing quantity under the usual conditions. Equating marginal revenue and marginal cost determines quantity when marginal cost is rising through marginal revenue. Profit can still be negative.
A competitive firm and a monopolist both maximize profit using MR=MC. The key difference is that
- only the competitive firm uses marginal cost
- the competitive firm has MR=P, while the monopolist has MR<P
- only the monopolist can earn a short-run profit
- the monopolist always produces at minimum ATC
- the competitive firm faces market demand
the competitive firm has MR=P, while the monopolist has MR<P A price taker sells each unit at market price, whereas a monopolist must lower price to expand sales, placing MR below demand.
A cost worksheet lists $2,700 in the total-cost column beside an output of 90. The corresponding average total cost is
- $30
- $90
- $180
- $2,610
- $2,790
$30 per unit Average total cost is $2,700 ÷ 90 units = $30 per unit. The firm must compare that unit cost with its price to determine profit or loss.
Video Lesson: Production, Cost and Revenue
A focused video lesson from The Learning Studio.
Connect Physical Production to Cost
A firm transforms inputs into output and compares the revenue created with the opportunity cost of resources. In the short run, at least one input is fixed. Adding variable input eventually produces diminishing marginal product, which makes marginal cost rise: when each extra worker adds less output, more labor cost is required for another unit.
Separate Total, Average and Marginal Cost
Cost identities organize the schedules. TC=FC+VC and ATC=AFC+AVC. MC is the change in total or variable cost from another unit because fixed cost does not change with output. MC crosses AVC and ATC at their minima through the marginal-average rule. In the long run all inputs vary. Economies, constant returns, and diseconomies of scale shape LRAC.
Choose Output Before Calculating Profit
Under the usual smooth, interior-output conditions, expand while MR exceeds MC and identify the appropriate MR-MC crossing; also compare feasible boundaries and shutdown. Market structure determines MR. A competitive firm has P=MR. A monopolist lowers price to sell more, so MR lies below demand. Profit is still (P-ATC)Q, not the gap between MR and MC.
Compare Market Structures
| Structure | Firm demand | Long-run hallmark |
|---|---|---|
| Perfect competition | Horizontal at market price | Entry drives profit to zero |
| Monopoly | Market demand, downward | Barriers can sustain profit |
| Monopolistic competition | Downward for a variety | Entry, zero profit, excess capacity |
| Oligopoly | Depends on rival responses | Strategic interdependence |
Compare Operating with Short-Run Shutdown
Short-run operation depends on AVC. If price covers AVC, producing can pay variable cost and part of fixed cost, even when profit is negative. Long-run survival depends on covering all economic cost. Entry and exit shift market supply and change the price facing competitive firms.
Read Monopoly Price from Demand
Monopoly chooses quantity where MR equals MC, then reads price from demand. It generally restricts output below the competitive level, transfers surplus through higher price, and creates DWL on lost trades. Price discrimination can change output and distribution. Oligopoly requires best responses: a Nash equilibrium occurs when no player benefits from changing alone.
Connect Input Choice with Revenue
Input choice completes the connection. If one adjustable input produces more extra output per dollar than another, shifting spending toward it lowers the cost of the target output. An interior least-cost combination removes that gap. Labor demand then values physical productivity through MRP=MP× MR. Technology, product price, wages, and market structure therefore form one causal system rather than separate chapters.
Follow the Production-to-Profit Decision Map
A final decision map helps: production data generate MP, input prices convert production into cost, market structure generates MR, and the MR-MC comparison selects output. Demand then determines price when the firm has market power, while market price is given under competition. ATC at the chosen output determines profit. Following that order prevents using ATC to select quantity or using MR as monopoly price.
Rehearse the order as questions: What does the next input add? What does the next output unit cost? What revenue does that unit create under this market structure? Which quantity passes the marginal test? What price applies there? Does price cover AVC and ATC? Only after those questions should entry, exit, price discrimination, strategic response, or excess capacity enter the analysis. The sequence keeps a correct fact about one market structure from becoming a distractor in another.
Check the Conditions Behind the Marginal Rule
OpenStax’s competitive-firm output discussion distinguishes the output decision from profit and shutdown. MR = MC does not imply positive profit: compare price with ATC at the chosen quantity. For the standard short-run model, an operating loss can be smaller than the loss from shutting down when revenue covers variable cost and contributes toward unavoidable fixed cost.
Its monopoly output and price section uses demand to find the price associated with the chosen quantity. Do not use marginal revenue as the sale price. This is the single-price model; price discrimination requires additional analysis.
The short-run cost section connects input quantities and input prices with total, average and marginal costs. Fixed cost is unchanged by another output unit in this model, so the change in total cost equals the change in variable cost. When using the table above on a phone, focus it and use horizontal arrow keys to reach every column.
Calculate a Loss Without Confusing It with Shutdown
A hypothetical competitive firm’s best operating quantity is 4 units. Price is $9, ATC is $11 and AVC is $5 at that quantity. Assume its fixed cost is unavoidable in the short run and there are no other relevant costs. Is producing necessarily worse than shutting down?
Check your reasoning
No. Producing gives revenue of $36, total cost of $44 and a loss of $8. Variable cost is $20, leaving fixed cost of $24. Shutting down avoids variable cost but still leaves that $24 fixed cost. Operating loses $8 rather than $24 in this hypothetical short run. This does not establish long-run viability: the firm still fails to cover all economic cost.
Try Three Output and Profit Questions
Choose one answer, then check your reasoning. These are short learning checks, not an exam score. If the controls are unavailable, the explanations remain readable below each question.
Answer C. The marginal change is $10 − $7 = $3. This tells you how the extra unit changes profit, not the firm’s total profit or its average cost.
Answer A. Revenue is $120 and total cost is $144, giving a $24 loss. A marginal output rule does not by itself guarantee a positive level of economic profit.
Answer D. For a single-price monopolist, select quantity using the marginal comparison under the usual conditions, then read price from demand. MR below price reflects the revenue effect of lowering the price to sell more.
Continue Connecting the Firm to Its Markets

Reza is an experienced Math instructor and a test-prep expert who has been tutoring students since 2008. He has helped many students raise their standardized test scores--and attend the colleges of their dreams. He works with students individually and in group settings, he tutors both live and online Math courses and the Math portion of standardized tests. He provides an individualized custom learning plan and the personalized attention that makes a difference in how students view math.
Related to This Article
More math articles
- Government Economic Policy and Market Failures
- ACT Math Test-Taking Strategies
- What Are the 12 Algebraic Formulas?
- How to Use a Calculator on Standardized Math Tests
- 7th Grade North Carolina End-of-Grade Math Worksheets: FREE & Printable
- The Best Algebra 1 Book for Indiana Students
- How to Solve Point-Slope Form of Equations?
- Top 10 ASVAB Math Prep Books (Our 2027 Favorite Picks)
- 3rd Grade Common Core Math FREE Sample Practice Questions
- Family and Religion


What people say about "Marginal Revenue and Marginal Cost: Output, Price and Profit"?
No one replied yet.