Industry Cost Conditions: Constant, Increasing and Decreasing
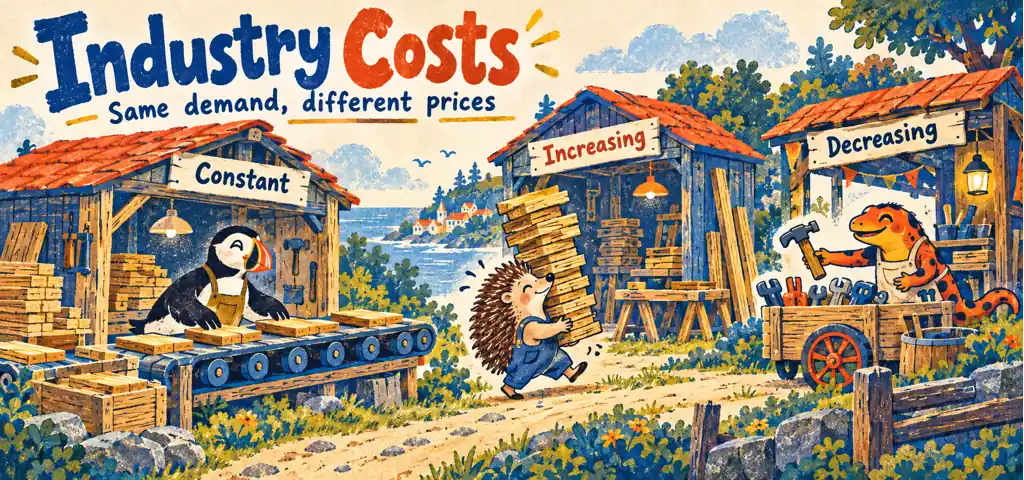
Industry cost conditions explain why entry does not always restore the old price. Compare constant, increasing and decreasing industry costs, calculate three long-run outcomes, then check your understanding with original interactive questions.
Entry can change input prices and external economies.
Compare Two Long-Run Cases
Use the competitive long-run benchmark: identical price-taking firms, free entry and exit, a lasting demand change and no separate technology shock. Firms cover all economic costs, including opportunity costs, at the endpoint. Industry expansion may change input costs available to every firm; the type of industry tells you how. These results describe the stated model, not every real market.
In an increasing-cost industry, a permanent increase in demand leads to a long-run price that is
- below its original level after firms enter
- equal to its original level as in a constant-cost industry
- zero because entry eliminates all accounting profit
- indeterminate because long-run output cannot change
- above its original level as industry input costs rise
above its original level as industry input costs rise Expansion bids up specialized inputs or otherwise raises firms’ costs, so the long-run supply curve slopes upward.
A constant-cost competitive industry expands after demand rises. In the new long-run equilibrium, each representative firm most likely
- produces above efficient scale at a higher average cost
- returns to efficient scale while more firms serve the market
- retains positive economic profit after entry is complete
- faces a price below the industry’s original minimum cost
- operates at an output below minimum average total cost
returns to efficient scale while more firms serve the market At the restored constant-cost price, representative firms again operate at minimum ATC. Industry output expands through entry.
Video Lesson: Industry Cost Conditions
A focused video lesson from Economics classes.
Connect Price with Minimum ATC
With unchanged firm costs, entry can restore the initial zero-profit price. If industry expansion raises firms’ minimum ATC, the new long-run price must cover that higher cost. If expansion instead lowers minimum ATC, a lower zero-profit price can support the larger industry. Zero economic profit alone does not tell you whether the new price equals the old one.
Identify the Industry-Wide Cost Effect
Ask what happens to an otherwise comparable firm as the industry grows. Competition for a scarce specialized input can raise its input price. A larger supplier network can lower the delivered cost of an input available to many firms. Those are industry-wide effects on the firm’s cost schedule; neither requires that the individual firm become larger.
Compare Three Industry Types
| Industry type | Long-run supply | Demand increase endpoint |
|---|---|---|
| Constant cost | Horizontal | Price returns to original level |
| Increasing cost | Upward sloping | Price ends above original level |
| Decreasing cost | Downward sloping | Price can end below original level |
Separate Market and Firm Output
In the unchanged-cost identical-firm benchmark, entry changes seller count while each firm returns to its original minimum-ATC output. Market output and one firm’s output therefore need separate labels: Q for the industry and q for a firm. With a cost shift, calculate the new efficient q instead of assuming it must change or must stay fixed.
Check Whether Efficient Scale Changes
An industry-wide cost increase may change both the minimum ATC and the output at which it occurs. The direction of the efficient-scale change depends on the cost function. The numerical example below deliberately shifts costs without changing the minimizing q, showing why a higher price need not mean a larger firm.
Label the Curve You Are Reading
Long-run industry supply connects equilibria after entry, exit and relevant industry input-market adjustments. One competitive firm still takes the prevailing output price as given. Its horizontal demand line and its own MC curve answer different questions from the industry’s long-run supply schedule.
Test the Scarce-Input Mechanism
As a hypothetical case, suppose expansion increases demand for engineers whose services remain scarce over the relevant range. Higher wages can raise firms’ costs and the zero-profit price. This illustrates a mechanism; it is not a measured claim about all renewable-energy markets or a prediction that every input price must rise.
Distinguish External and Internal Economies
External economies differ from economies of scale within one firm. A firm’s own larger plant can lower its cost through internal scale economies. An external economy lowers a firm’s cost because the whole industry expands, even if that firm remains the same size. Identify the level causing the saving.
Use the Stated Assumptions
Read the stated cost assumptions before deciding the endpoint. If they are missing, state the conditional result rather than claiming that every economics exam defaults to a constant-cost industry. Entry by itself does not prove that inputs became more expensive; the reason for the cost change matters.
Keep Firm MC Separate
Constant industry costs do not mean flat MC for a firm. In the example below MC rises with q even in the constant-cost case. Conversely, an external cost saving as Q grows does not mean a firm can lower its own cost simply by expanding alone. Keep the two output variables separate.
Check the Relevant Range and Equilibrium
A downward-sloping long-run supply schedule also needs a compatible demand curve and an equilibrium-selection assumption. Do not extrapolate a local cost relationship indefinitely or assume that any intersection is stable. The worked example states its output range and checks a demand curve that is steeper than the decreasing-cost schedule.
Trace the Endpoint in Order
Start from the original long-run equilibrium, identify the lasting demand shift, then determine how expansion affects minimum ATC. Use the changed costs to find the new zero-profit price and the demand curve to find Q. Finally calculate firm output and seller count. A higher final price can coexist with zero economic profit because the economic costs changed.
Read the Underlying Entry and Exit Model
OpenStax’s entry and exit lesson discusses how industry growth can change firms’ costs. The following equations, numbers and practice questions are original teaching examples, not adapted textbook exercises.
Calculate Three Different Endpoints
Let one firm’s total economic cost be TC = q² + 100 + c(Q)q. Each small price-taking firm treats industry output Q and the industry input-cost component c(Q) as given when choosing its own q. These dollar costs include the normal return required to remain in the industry. There is free entry and exit among identical firms.
For positive q, ATC = q + 100/q + c(Q). Its minimum is 20 + c(Q) at q = 10, since ATC − [20 + c(Q)] = (q − 10)²/q. MC = 2q + c(Q), so the competitive condition P = MC also holds at that minimum. A changed input-cost component shifts the zero-profit price while efficient output remains ten in this particular model.
Initially P = 60 − Q/15. All three cases share c(300) = 20, so Q = 300, P = $40, q = 10 and thirty firms form the initial equilibrium. Now shift demand to P = 70 − Q/15. Compare three hypothetical cost relationships, used only over Q = 300 to 600: constant c(Q) = 20; increasing c(Q) = 20 + (Q − 300)/30; and decreasing c(Q) = 20 − (Q − 300)/30. The input component stays positive throughout this range.
| Industry cost | Final price | Industry Q | Firms | q per firm | Economic profit per firm |
|---|---|---|---|---|---|
| Constant | $40 | 450 | 45 | 10 | $0 |
| Increasing | $43⅓ | 400 | 40 | 10 | $0 |
| Decreasing | $30 | 600 | 60 | 10 | $0 |
Set the new demand price equal to minimum ATC. Constant costs give 70 − Q/15 = 40, hence Q = 450. Increasing costs give 70 − Q/15 = 40 + (Q − 300)/30, hence Q = 400 and P = $43⅓. Decreasing costs give 70 − Q/15 = 40 − (Q − 300)/30, hence Q = 600 and P = $30. Divide Q by ten to obtain the seller counts. All three outcomes have more output than the initial 300; their prices move differently.
Check Profit and the Decreasing-Cost Intersection
Why does a price of $43⅓ not imply excess profit here, and why is the decreasing-cost intersection usable over the stated range?
Check your reasoning
At Q = 400, c(Q) = 23⅓. A firm producing ten units has revenue $433⅓ and cost 100 + 100 + $233⅓ = $433⅓, so economic profit is zero. At Q = 450 in the constant-cost case, revenue and cost both equal $400. At Q = 600 in the decreasing-cost case, c(Q) = 10 and revenue and cost both equal $300.
The new inverse demand slope is −1/15, while the decreasing-cost zero-profit schedule has slope −1/30. Their price difference is 20 − Q/30: positive below Q = 600 and zero at 600. Under a quantity-adjustment rule that expands output when demand price exceeds the zero-profit supply price, this moves toward the endpoint from within the stated range. It is a local model check, not a claim about every decreasing-cost market or an invitation to extend the formula outside Q = 300 to 600.
For a fixed industry input component, operating profit is (P − c)²/4 − 100 − [q − (P − c)/2]². At each endpoint P − c = 20, so q = 10 maximizes firm profit and gives zero. The firm does not choose the whole industry’s Q or internalize a change in every supplier’s costs.
Try Three Industry Cost Questions
Choose one answer, then check your reasoning. These are short learning checks, not an exam score. If the controls are unavailable, the explanations remain readable below each question.
Answer C. Set 70 − Q/15 = 40 to get Q = 450. Each identical firm produces ten at minimum ATC, so there are forty-five firms. Price remains $40 and each firm earns zero economic profit.
Answer A. Revenue is ten times $43⅓, or $433⅓. Total cost is 100 + 100 + $233⅓ = $433⅓. The higher output price covers higher input costs; it does not create a permanent excess-profit gap.
Answer D. The supplier improvement comes from expansion of the industry and benefits otherwise comparable firms. A larger machine is an internal scale change. Higher specialist wages illustrate an external diseconomy instead.
Connect Costs with Entry and Market Structure

Reza is an experienced Math instructor and a test-prep expert who has been tutoring students since 2008. He has helped many students raise their standardized test scores--and attend the colleges of their dreams. He works with students individually and in group settings, he tutors both live and online Math courses and the Math portion of standardized tests. He provides an individualized custom learning plan and the personalized attention that makes a difference in how students view math.
Related to This Article
More math articles
- 8th Grade MCA Math Worksheets: FREE & Printable
- What Kind of Math Is on the ASVAB Test?
- AFOQT Math FREE Sample Practice Questions
- Double the Steps, Double the Fun: How to Solve Two-Step Inequalities
- The Best Grade 3 Math Book for South Dakota Students
- Area and Perimeter
- Community
- Drawing Conclusions and Making Predictions
- Series Convergence Calculator
- Cultural Lag, Modernization, and Globalization


What people say about "Industry Cost Conditions: Constant, Increasing and Decreasing"?
No one replied yet.