Pollution Taxes, Tradable Permits and Standards
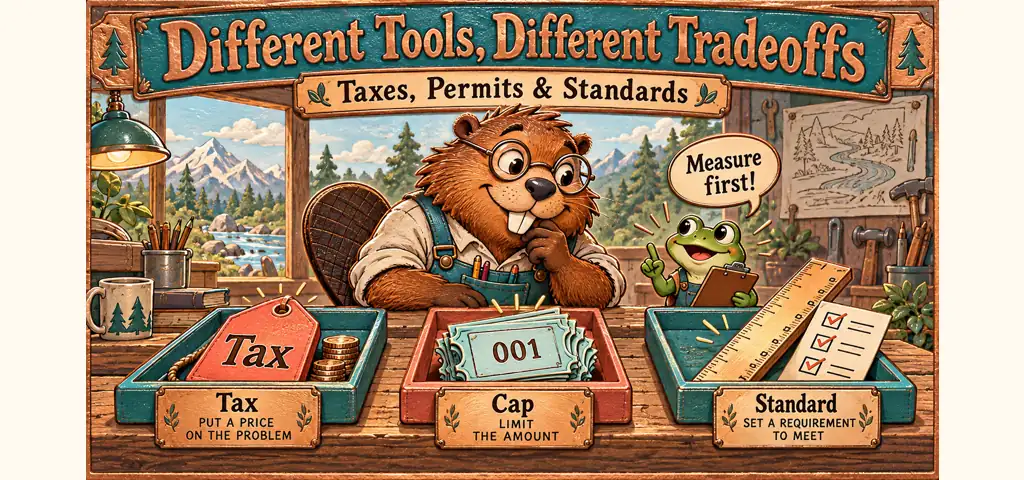
Pollution taxes, tradable permits and standards control different margins. A tax fixes a charge per covered unit, a fixed absolute cap limits covered emissions, and a standard may constrain an emissions rate or technology. Compare what each policy changes, what information it needs, and which choices remain with firms. A label alone does not establish effectiveness or fairness.
The efficient target does not automatically identify the best instrument.
Read Two Cost-Effectiveness Examples
Tradable emissions permits can achieve a pollution target at lower total cost because
- every firm receives the same abatement technology
- permits eliminate the need to monitor emissions
- the permit price is always zero
- low-cost firms abate more and sell unused permits
- government learns every firm’s cost before setting the cap
low-cost firms abate more and sell unused permits With enforceable monitoring, feasible trading and equivalent covered tons, trading can direct abatement toward lower-cost sources while preserving the fixed overall cap. Cost savings alone do not establish that the cap is optimal or that local pollution effects are equivalent.
Two factories face abatement costs of $12 and $30 for one additional ton. If one extra ton must be eliminated, cost effectiveness requires that
- the $12 factory perform the reduction
- each factory reduce half a ton regardless of cost
- the $30 factory reduce because it has higher cost
- neither factory reduce without a tax
- both factories receive identical equipment
the $12 factory perform the reduction Assigning the reduction to the factory with the lower $12 marginal abatement cost achieves the target at least cost.
Video Lesson: Tradable Permits and Pollution Taxes
A focused video lesson from Mike Dennis.
Identify What the Instrument Controls
A corrective tax sets a price for the harmful activity but leaves the final pollution quantity responsive to firms’ costs. In a simple fixed-cap model, cap-and-trade limits covered emissions over a stated period and lets the allowance price adjust. Rate-based programs and designs with changing budgets require separate analysis. A uniform standard can be simple to explain but may force high- and low-cost firms to make the same reduction. Tradable permits can lower total compliance cost by shifting abatement toward firms that can reduce pollution cheaply.
Check Measurement, Enforcement and Distribution
Every instrument requires monitoring. A tax requires measurable emissions, permits require a defensible cap and enforcement, and bargaining requires identifiable parties and sufficiently low transaction costs. Distribution also matters: auctioned permits create public revenue, freely allocated permits give valuable rights to recipients, and a tax can burden consumers through higher product prices. For the simple benchmark, hold marginal benefits and resource costs fixed while examining these distributional effects. Real income effects, other distortions and distributional objectives can matter in a broader policy assessment.
Match the Corrective Charge to Marginal Damage
In the standard competitive benchmark without other distortions, a corrective charge equals marginal external damage at the efficient quantity of the activity being taxed. Match the units: a charge per ton of emissions must use damage per additional ton, not damage per unit of product. Average damage and the largest visible cleanup bill are not automatically the right rate.
Separate an Efficient Target from a Cost-Effective Method
Policy comparison begins with a common benchmark: the efficient quantity is where marginal social benefit equals marginal social cost. Once that target is clear, compare instruments on accuracy, compliance cost, enforcement, distribution, and incentives to innovate. A policy that reaches the same emissions total at lower real resource cost is more cost-effective, but cost-effectiveness alone does not answer every fairness or administrative question.
Compare the Cost of the Same Feasible Reduction
Suppose two factories must jointly reduce emissions by ten tons. Factory R can remove each ton for $20, while Factory S faces $80 per ton. Requiring five tons from each costs $500. Allowing R to make all ten reductions costs $200, provided ten reductions are feasible for R and its marginal cost stays at $20. Assume the covered pollutant’s damage is equivalent across these sources and times, so the same number of tons reduced gives the same environmental result. A tradable system or common emissions price gives the firms an incentive to discover that lower-cost allocation. The saving is real: fewer labor and capital resources are used to achieve the same environmental result.
Compare Four Policy Instruments
| Instrument | Government fixes | Firms choose | Central risk |
|---|---|---|---|
| Emissions tax | Price per harmful unit | Final emissions and abatement | Quantity uncertain |
| Fixed-cap tradable permits | Total permitted quantity | Trading and who abates | Permit price uncertain |
| Performance standard | Maximum rate or amount | Compliance method, if flexible | Cost differences may be missed |
| Technology rule | Required equipment | Little technological discretion | Can freeze an inferior method |
Account for Valuable Allowances and Household Burdens
Distribution must be separated from efficiency. Auctioned permits and pollution taxes raise public revenue. Freely allocated permits give recipients an asset but can still create an opportunity cost: using a permit means forgoing its sale. Consumers may bear part of a tax through higher product prices, depending on elasticities. Those incidence comparisons do not by themselves identify a new efficient quantity when the benchmark marginal benefit and cost schedules are held fixed. They still affect household burdens and political feasibility; income effects, pre-existing distortions or distributional objectives can change a broader evaluation.
Examine Incentives to Improve the Method
Dynamic incentives matter too. A fixed technology mandate may produce compliance yet give little reward for inventing a cleaner process once the rule is met. An emissions price rewards every additional reduction that costs less than the tax or permit price. On the other hand, monitoring actual emissions may be difficult, making an equipment standard easier to verify in some settings.
Choose from the Actual Conditions
Avoid two shortcuts. First, “market-based” does not mean unregulated: permit systems require a cap, definitions, tracking, and penalties. Second, direct regulation is not automatically inefficient: it can work well when damages are severe, monitoring choices is easy, or only one safe method exists. The best instrument follows from the facts in the stem.
Trace the Mechanism in One Policy Chain
For exam decisions, write a one-line policy chain: failure → missing incentive → instrument → behavioral response → new quantity. If any link is absent, a distractor may name a popular policy without explaining how it corrects the stated problem.
Read the Framework and Its Limits
OpenStax’s environmental-tools chapter explains how charges and tradable permissions can change incentives while allowing choices about abatement. The relevant comparison is the cost of achieving a specified result, rather than a claim that any market-based policy must work well.
The EPA’s emissions-trading explanation describes caps, allowances and compliance, including designs with location- or time-specific safeguards. Its key terms distinguish mass-based limits, rate-based approaches, monitoring and allowance allocation. A lower emissions rate is not necessarily a lower total when output grows.
State the coverage, period and measurement method. Check whether a ton emitted at one source has the same effect as a ton elsewhere before calling two allocations environmentally equivalent. Tracking, enforcement, trading costs and market power can affect whether the simple cost-minimization benchmark is reached. These introductory comparisons do not specify a current program’s legal limits or rules.
Calculate Total Emissions from a Rate and Output
In an invented example, a plant initially produces 100 units with emissions of 2 kilograms per unit. It lowers its emissions rate by 30% while output rises by 20%. Does total pollution fall by 30%?
Check your reasoning
Initial emissions are 100 × 2 = 200 kilograms. The new rate is 2 × 0.70 = 1.4 kilograms per unit and output is 100 × 1.20 = 120 units. New total emissions are 120 × 1.4 = 168 kilograms. The total falls by 32 kilograms, or 16%, rather than 30%.
The proportional shortcut is 0.70 × 1.20 = 0.84, leaving 84% of the initial total. A rate improvement and an absolute cap constrain different quantities. This arithmetic does not tell you whether the resulting total is environmentally sufficient; that requires a separate target and evidence about damage.
Try Three Policy-Comparison Questions
Choose one answer, then check your reasoning. These are short learning checks, not an exam score. If the controls are unavailable, the explanations remain readable below each question.
Answer B. Using the allowance gives up a possible $25 sale. Abating for $10 allows the sale, producing a $15 gain relative to using it. Free initial allocation does not remove that opportunity cost. This hypothetical assumes the transfer is allowed and all other effects are unchanged.
Answer D. Total emissions equal emissions per unit times output. Multiply the remaining rate factor 0.80 by the output factor 1.40: the result is 1.12, or 112% of the original total. A lower rate can coexist with a higher total.
Answer C. Equal totals need not mean equal damage when effects depend on where or when pollution occurs. A cost-effectiveness comparison must define an equivalent environmental result; local safeguards and the relevant damage pattern can matter.
Connect Incentives, Resources and Evidence

Reza is an experienced Math instructor and a test-prep expert who has been tutoring students since 2008. He has helped many students raise their standardized test scores--and attend the colleges of their dreams. He works with students individually and in group settings, he tutors both live and online Math courses and the Math portion of standardized tests. He provides an individualized custom learning plan and the personalized attention that makes a difference in how students view math.
Related to This Article
More math articles
- Full-Length 7th Grade FSA Math Practice Test
- Migration, Citizenship, and Belonging
- How to Solve Radical Inequalities?
- Louisiana LEAP Algebra 1 Free Worksheets: Free Algebra 1 PDF Worksheets with Clear Answer Keys
- 3rd Grade Georgia Milestones Assessment System Math Worksheets: FREE & Printable
- The Best Grade 6 ELA Practice Tests for Arizona Students
- The Best Grade 7 Math Book for California Students
- Pace Calculator
- A Comprehensive Collection of Free CLEP College Algebra Practice Tests
- Integral Approach to Cumulative Growth












What people say about "Pollution Taxes, Tradable Permits and Standards"?
No one replied yet.