Firm vs. Market Curves: Demand, Supply and Competitive Price
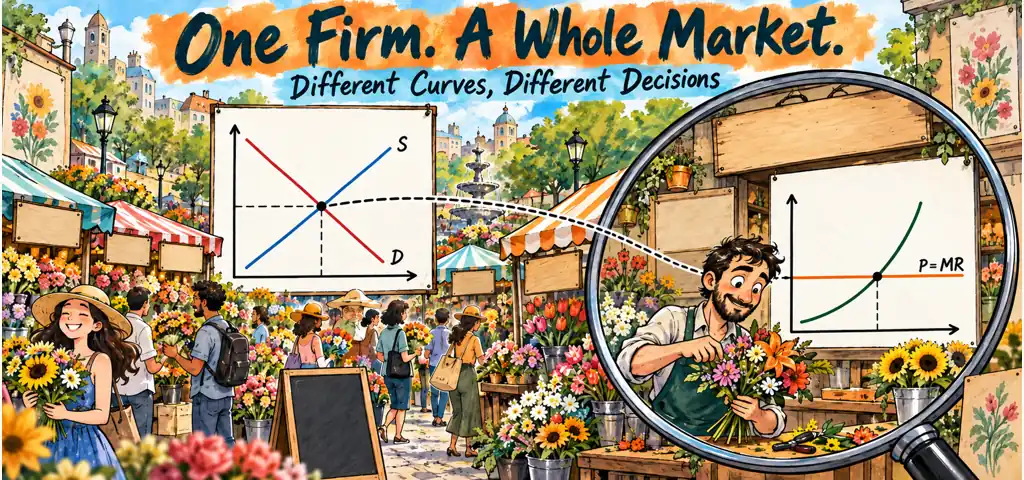
A competitive firm faces horizontal demand at the price determined by the market. The market diagram combines buyers and sellers; the firm diagram describes one seller’s output decision. Label market quantity Q and firm quantity q, then identify whether a change affects market conditions, the firm’s costs or both.
Keep the level of analysis visible.
Read Two Firm-versus-Market Examples
At a price of $10, each of 50 identical firms supplies 8 units. What is market quantity supplied at that price?
- 8 units
- 50 units
- 58 units
- 400 units
- 500 units
400 units The market curve horizontally sums firm quantities at the same price: 50 firms × 8 units per firm = 400 market units. One firm’s 8-unit point is not the market’s 400-unit point.
Demand for the market product rises, increasing the competitive market price from $14 to $17. What changes on one price-taking firm’s graph?
- The firm’s marginal-cost curve becomes the market supply curve
- The firm’s horizontal demand and marginal-revenue line moves up to $17
- The firm’s demand curve shifts down because market quantity rose
- The market demand curve is copied onto the firm graph
- The firm’s output must equal market output
The firm’s horizontal demand and marginal-revenue line moves up to $17 The demand shift occurs on the market graph and changes the price. The firm graph receives that new price as a horizontal line, then uses its own marginal cost to choose firm output.
Video Lesson: Graphing a Competitive Firm
A focused video lesson from You Will Love Economics.
Carry the Market Price onto the Firm Graph
Market demand slopes down even though a competitive firm’s demand is horizontal. Market equilibrium determines price. The firm takes that price and chooses its own output. Exit shifts market supply but does not shift the cost curves of a remaining constant-cost firm. A monopolist faces market demand because it is the sole seller.
Explain Why a Short-Run Answer Can Be Incomplete
A competitive firm earns positive profit. The question asks for the long-run market price. “The firm produces more where P=MC” is true in the short run but incomplete. In the standard free-entry competitive model, profit attracts entry, market supply shifts right and price falls toward the zero-economic-profit outcome; hold the relevant demand and cost assumptions fixed.
Use the Comparison Table to Diagnose Confusion
| If two options seem close | Ask this deciding question |
|---|---|
| Demand vs. quantity demanded | Did the good’s own price change? |
| MC vs. ATC | Is the question about one more unit or cost per unit? |
| Shutdown vs. exit | Are fixed costs unavoidable in the stated horizon? |
| Profit vs. producer surplus | Have all fixed and implicit costs been subtracted? |
| Private vs. efficient quantity | Is an external cost or benefit missing? |
Name the Level Behind a Mistake
After every miss, write: “I chose ___ because I confused ___ with ___.” A precise diagnosis changes future performance. Copying the correct letter does not.
Keep Industry and Individual Quantities Separate
Market curves combine many buyers or sellers, while a firm’s curves describe one decision maker. In perfect competition, market demand slopes downward and market supply slopes upward, determining the price. The individual firm then faces horizontal demand at that price because it can sell its small output without materially changing the market total.
Quantities reveal the level. If market equilibrium output is one million units and a representative firm produces 2,000, transferring one million to the firm graph is an error. Industry quantity is the horizontal sum of firms’ quantities at each price. The firm selects its own output where market price equals MC.
Trace Entry Through the Market Price
Competitive firms earn profit at a market price of $25. Entry adds sellers, shifting market supply right and reducing price. For each incumbent, the horizontal demand line moves downward. Entry does not directly shift an incumbent’s MC or ATC if input prices and technology are unchanged.
Check the Market Structure Before Drawing Demand
A monopolist is different because the firm is the industry. It faces market demand, which slopes down, and its MR lies below that demand. A monopolistically competitive firm also faces downward demand, not because it is the only market seller, but because its differentiated variety has some pricing power. Market structure, not the word “firm,” determines the demand curve.
Separate Market Labor Supply from Employer Supply
Factor markets have the same levels. Market labor demand horizontally sums employers’ labor demands and interacts with market labor supply to determine a competitive wage. One small employer takes that wage as given. A monopsonist, by contrast, faces an upward-sloping labor supply to the firm and MRC above it.
Track a Tax or Fixed Fee at the Correct Level
Cost changes can propagate differently. A tax on every industry’s output shifts market supply. On one competitive firm’s diagram, a per-unit tax shifts MC and AVC upward. A fixed fee raises ATC but not MC. If firms exit later, market supply changes again. Keeping the time horizon and level separate prevents double counting.
Use Q, q and a Stated Time Horizon
Use notation and nouns deliberately: market Q, firm q. Market price, firm output. Industry entry, incumbent cost. Before choosing an option, ask whether it describes a curve shift for one decision maker or aggregation across many. A statement can be true at one level and false at the other, which is precisely why these distractors are effective.
Check the Competition and Entry Assumptions
OpenStax’s perfect-competition section treats an individual producer as too small to materially change the market price. That is the price-taking assumption, not a statement that every real firm faces horizontal demand. At one common price, add the quantities offered by all firms to construct market supply; do not add their prices.
The entry and exit section distinguishes a short-run output adjustment from a change in the number of firms. In a constant-cost benchmark with unchanged technology and input prices, entry shifts market supply without directly shifting an incumbent’s MC or ATC. Zero economic profit includes the opportunity cost of the owner’s resources; it does not mean zero revenue.
The imperfect labor-market section examines monopsony. If an employer must pay the same higher wage to existing workers to attract another worker, added labor expense can exceed that new worker’s wage. Do not transfer the wage-taking employer’s horizontal supply assumption into that model.
Add Firm Quantities at the Same Price
At a price of $12, three hypothetical competitive firms offer 4, 7 and 9 units respectively. A demand change then raises the market price to $15. With each firm’s costs unchanged, which information can you transfer between the two diagrams?
Check your reasoning
At $12, market quantity supplied is 4 + 7 + 9 = 20 units. At the new $15 price, each price-taking firm faces a horizontal price-and-MR line at $15. Its own cost conditions determine its output. You cannot carry the old market total of 20 units onto each firm graph, or calculate the new market total without the firms’ quantities supplied at $15.
Try Three Firm-and-Market Curve Questions
Choose one answer, then check your reasoning. These are short learning checks, not an exam score. If the controls are unavailable, the explanations remain readable below each question.
Answer C. Horizontal summation adds quantities at a common price: 3 + 5 + 8 + 10 = 26 units. An average firm quantity is not the industry total.
Answer A. The firm takes the new market price as given. A market demand shift need not change the firm’s cost curves. Its output response depends on its own costs and operating decision.
Answer D. Additional sellers add quantities to market supply. The lower resulting price moves each price-taking firm’s horizontal demand line downward. Unchanged input prices and technology do not by themselves shift the incumbent’s cost curves.
Connect Output Decisions with Market Equilibrium

Reza is an experienced Math instructor and a test-prep expert who has been tutoring students since 2008. He has helped many students raise their standardized test scores--and attend the colleges of their dreams. He works with students individually and in group settings, he tutors both live and online Math courses and the Math portion of standardized tests. He provides an individualized custom learning plan and the personalized attention that makes a difference in how students view math.
Related to This Article
More math articles
- How to Solve Pythagorean Theorem Problems? (+FREE Worksheet!)
- 3rd Grade NSCAS Math Worksheets: FREE & Printable
- 3rd Grade MAAP Math Worksheets: FREE & Printable
- Hard and soft money
- The Best Grade 6 ELA Practice Tests for Indiana Students
- How to Support Grade 8 Reading at Home: 12 Smart Strategies That Build Independence
- How to Perform Similarity Transformations: Step-by-Step Guide
- Everything you Need to know about Limits
- How to Pass the HiSET Math Test: 2026 Strategy Guide
- Collective Behavior and Routine Organization












What people say about "Firm vs. Market Curves: Demand, Supply and Competitive Price"?
No one replied yet.