Short-Run vs Long-Run Adjustment in Competition
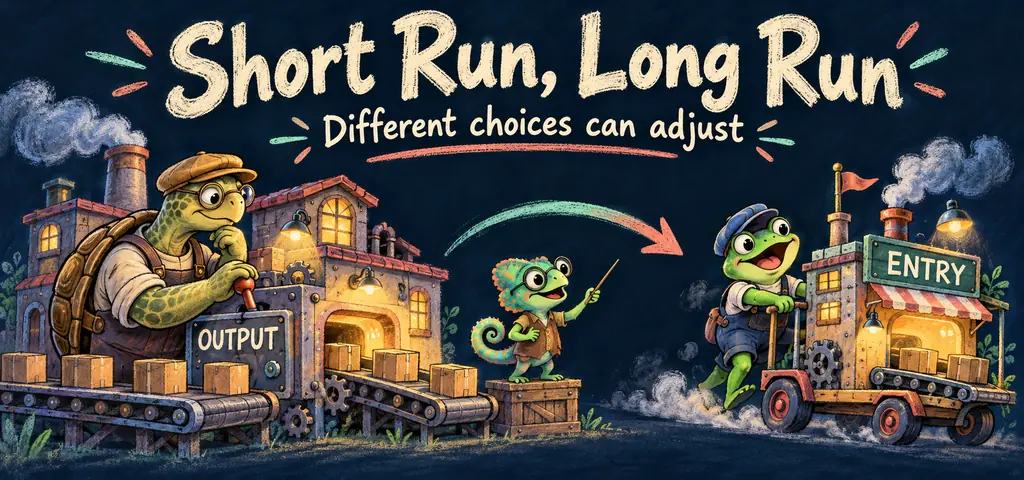
Short-run and long-run adjustment answer different questions about the same demand change. Existing competitive firms can change output before entry or exit changes the number of firms. Track price, output per firm, industry output and economic profit separately, then try three original interactive questions.
The same demand increase can have two different price effects over time.
Compare Three Entry and Exit Cases
The constant-cost cases start in long-run competitive equilibrium with identical firms, free entry and exit, unchanged technology and input prices, and a lasting demand shift. The short run allows variable-input and output adjustment while fixed inputs and seller count remain fixed. It is not the instant before any output can respond. Long-run zero economic profit is the endpoint under these assumptions, not a claim about every firm at every time.
Demand for a competitive product increases in a constant-cost industry. Which sequence best describes adjustment?
- Price falls, firms exit, and long-run output returns to its original level.
- Price remains fixed immediately, so no firm changes output.
- Price rises, firms exit, and supply shifts left.
- Demand returns to its original position after firms expand.
- Price and profit first rise. Entry later restores the original price.
Price and profit first rise. Entry later restores the original price. The demand increase raises short-run price and profit. Entry shifts supply right until price returns to the constant-cost level at a larger industry output.
Which event causes exit from a competitive industry?
- Price exceeds minimum ATC.
- Firms earn normal profit.
- Accounting profit is positive but economic profit is zero.
- Price remains below ATC in the long run.
- Demand rises temporarily.
Price remains below ATC in the long run. A price persistently below ATC means firms cannot cover all opportunity costs, inducing some to leave.
Market demand for a constant-cost competitive product increases. Compared with the original equilibrium, after full long-run adjustment
- price is higher and the number of firms is unchanged
- price is lower and each firm produces more
- price is indeterminate
- price is unchanged and the industry contains more firms
- price is unchanged and industry output is unchanged
price is unchanged and the industry contains more firms Entry expands industry output and restores the original constant-cost price. The long-run industry has more firms.
Video Lesson: Long-Run Competitive Profit
A focused video lesson from Khan Academy.
Trace a Lasting Demand Increase
In the stated short-run adjustment after demand rises, the number of firms is fixed but existing firms can change variable inputs and move along their MC curves. With upward-sloping market supply and an initial zero-profit equilibrium, price, output per firm and economic profit rise. Entry subsequently expands market supply. In the constant-cost model, unchanged minimum ATC restores the original long-run price at a larger market output and seller count.
Read the Four-Stage Timeline
Build a timeline rather than placing all curves on one undifferentiated graph:
| Stage | Market | Representative firm |
|---|---|---|
| Initial long run | Price at minimum ATC | Zero economic profit |
| Short run after demand rise | Demand right. Price and Q rise |
P=MR rises. q and profit rise |
| Entry process | Supply shifts right | Price and incumbent profit fall |
| New long run | Higher market Q. Benchmark price restored |
Efficient q. Zero economic profit |
Separate a Loss, Shutdown and Exit
For a lasting demand decrease under the same assumptions, short-run price and output per firm fall. Firms may incur economic losses while continuing to operate if revenue covers variable cost; otherwise short-run shutdown can be preferable. Long-run exit reduces market supply until surviving identical firms again earn zero economic profit. Shutdown for a period and leaving the industry are different choices.
Identify Which Adjustment Stage Is Asked
When the question asks about the short run after variable inputs adjust but before entry, the stated model gives a higher price, more output per existing firm and positive economic profit. After full constant-cost adjustment, it gives the original price, zero economic profit, more firms and greater market output. A question about fixed inventory before production responds needs a different market-period assumption.
Check the Industry Cost Assumption
Constant-cost industry means expansion does not change firms’ input prices and cost curves; it does not mean an individual firm’s MC must be constant. With increasing industry costs, the new long-run zero-profit price is above the original benchmark under the usual assumptions. With decreasing industry costs, it can be below it. Do not promise that entry always reverses a particular fraction of the short-run price change.
Separate Market Supply from Firm MC
Entry adds sellers and shifts market supply in the constant-cost model. It does not by itself shift an incumbent’s unchanged MC curve. The incumbent moves along that curve as price changes. If input prices or technology change, its costs can shift too; then use the relevant cost-changing assumptions rather than the constant-cost shortcut.
Keep the Entry Incentive Visible
Temporary profit is the incentive for entry in this model. Setting short-run profit to zero simply because a long-run endpoint exists removes the very adjustment mechanism being analyzed. Keep the observed stage and the equilibrium being approached separate.
Distinguish Economic and Accounting Profit
Economic cost includes explicit payments such as wages, rent and materials plus relevant opportunity costs, including forgone owner earnings and the normal return on capital. Zero economic profit means revenue covers those economic costs. It does not require zero accounting profit or zero compensation for the owner.
In a separate bookkeeping example, $200 revenue minus $170 explicit cost gives $30 accounting profit. If opportunity cost is $30, economic profit is zero. The labels differ because the cost measures differ, not because the business has no income or because one profit number is an arithmetic error.
Know When the Benchmark Changes
For a cost-changing event, the new long-run endpoint may use a different minimum ATC. Returning to the old price requires the unchanged constant-cost assumptions. Persistent differences between firms, barriers to entry or scarce firm-specific resources also require more detail than the identical-firm zero-profit benchmark.
Use the Timeline Without Skipping a Stage
A disciplined timeline names three stages: the initial equilibrium, the short-run firm response with seller count fixed, and the long-run entry or exit response. If the stem stops at one stage, do not import conclusions from the next. This sequencing is more reliable than memorizing that competitive profit “always becomes zero” without asking when.
Read the Entry and Exit Explanation
OpenStax’s long-run entry and exit lesson explains the technical time horizons, short-run losses, free-entry adjustment and different industry cost conditions. The equations and questions below are original examples, not copied textbook exercises.
Calculate a Constant-Cost Adjustment
Each identical firm has total economic cost TC = q² + $100 and MC = 2q. The $100 is unavoidable over the short-run operating period but avoidable when deciding whether to enter or exit. Costs and technology stay unchanged as the industry expands. Initial demand is Q = 200 − 5P, where Q is industry output and q is one firm’s output. Ten firms initially operate.
ATC is q + 100/q for positive q. It is at least $20 because ATC − 20 = (q − 10)²/q, with equality at q = 10. Thus P = $20 supports the initial long-run equilibrium: each firm produces 10 units, the industry produces 100 and each firm earns zero economic profit. Demand then shifts permanently to Q = 300 − 5P.
| Stage | Price | Firms | q per firm | Industry Q | Profit per firm |
|---|---|---|---|---|---|
| Initial long run | $20 | 10 | 10 | 100 | $0 |
| Short run, new demand | $30 | 10 | 15 | 150 | $125 |
| New long run | $20 | 20 | 10 | 200 | $0 |
Before entry, each firm chooses q = P/2, so ten firms supply Q = 5P. Set 5P = 300 − 5P to get P = $30, Q = 150 and q = 15. Revenue per firm is $450 and total cost is $325, leaving $125 economic profit. With free entry and unchanged costs, price returns to $20; demand is then 200, supplied by twenty firms producing ten units each. Firm output returns to ten while industry output doubles from its initial level.
Test a Separate Demand Decrease
Return to the original ten-firm equilibrium, then instead reduce demand to Q = 150 − 5P. What happens before exit, and why might a loss-making firm keep operating during the short run?
Check your reasoning
With ten firms, market supply is still Q = 5P. Equating it to the lower demand gives P = $15, Q = 75 and q = 7.5. One firm receives $112.50 revenue, has $56.25 variable cost and $100 unavoidable fixed cost, and earns −$43.75. Operating is preferable to the −$100 shutdown payoff because revenue more than covers variable cost. Its AVC is $7.50, below price, even though ATC is about $20.83.
After full long-run exit, unchanged costs again support P = $20 and q = 10. The lower demand then gives industry Q = 50, served by five firms. Output per surviving firm returns to ten; market output and the number of firms are below their initial levels. No fixed number of days or months defines these horizons: the distinction is which inputs and entry or exit decisions can adjust.
For any given positive price in these examples, a firm’s operating profit is P²/4 − 100 − (q − P/2)². The choice q = P/2 therefore maximizes operating profit. The separate comparison with shutdown and long-run exit completes the decision rather than assuming every loss forces immediate closure.
Try Three Adjustment Questions
Choose one answer, then check your reasoning. These are short learning checks, not an exam score. If the controls are unavailable, the explanations remain readable below each question.
Answer B. Each firm supplies q = P/2, so ten firms supply Q = 5P. Set 5P = 300 − 5P: P = $30 and q = 15. Revenue is $450 and total cost is $325, leaving $125 economic profit.
Answer D. At P = $20, demand is 300 − 5(20) = 200. Each identical firm produces 10 units at minimum ATC, so 20 firms serve the market. The $200 revenue per firm equals its $200 economic cost.
Answer A. Variable cost is 7.5² = $56.25 and revenue is $15 × 7.5 = $112.50. Operating contributes $56.25 toward unavoidable fixed cost, making total profit −$43.75. Shutdown would lose the whole $100 fixed cost. Long-run exit is a separate decision.
Connect Entry, Barriers and Market Structure

Reza is an experienced Math instructor and a test-prep expert who has been tutoring students since 2008. He has helped many students raise their standardized test scores--and attend the colleges of their dreams. He works with students individually and in group settings, he tutors both live and online Math courses and the Math portion of standardized tests. He provides an individualized custom learning plan and the personalized attention that makes a difference in how students view math.
Related to This Article
More math articles
- CPA AUD Blueprint: Audit Your Study Plan (2027 Prep)
- Preparing For SAT Math? DON’T Make These Big Mistakes!
- The Best Grade 7 Math Book for Oklahoma Students
- How to Fall in Love with Math and Studying?
- The Best Grade 4 Math Book for Texas Students
- The Sociological Imagination
- The Best Grade 4 ELA Practice Tests for Wisconsin Students
- ACT Math: Test-Taking Strategies
- Family, Household, Kinship, and Family Position
- The Best Grade 8 ELA Practice Tests for South Carolina Students


What people say about "Short-Run vs Long-Run Adjustment in Competition"?
No one replied yet.