CPA FAR Consolidations: Identify Elimination Entries (2027 Prep)
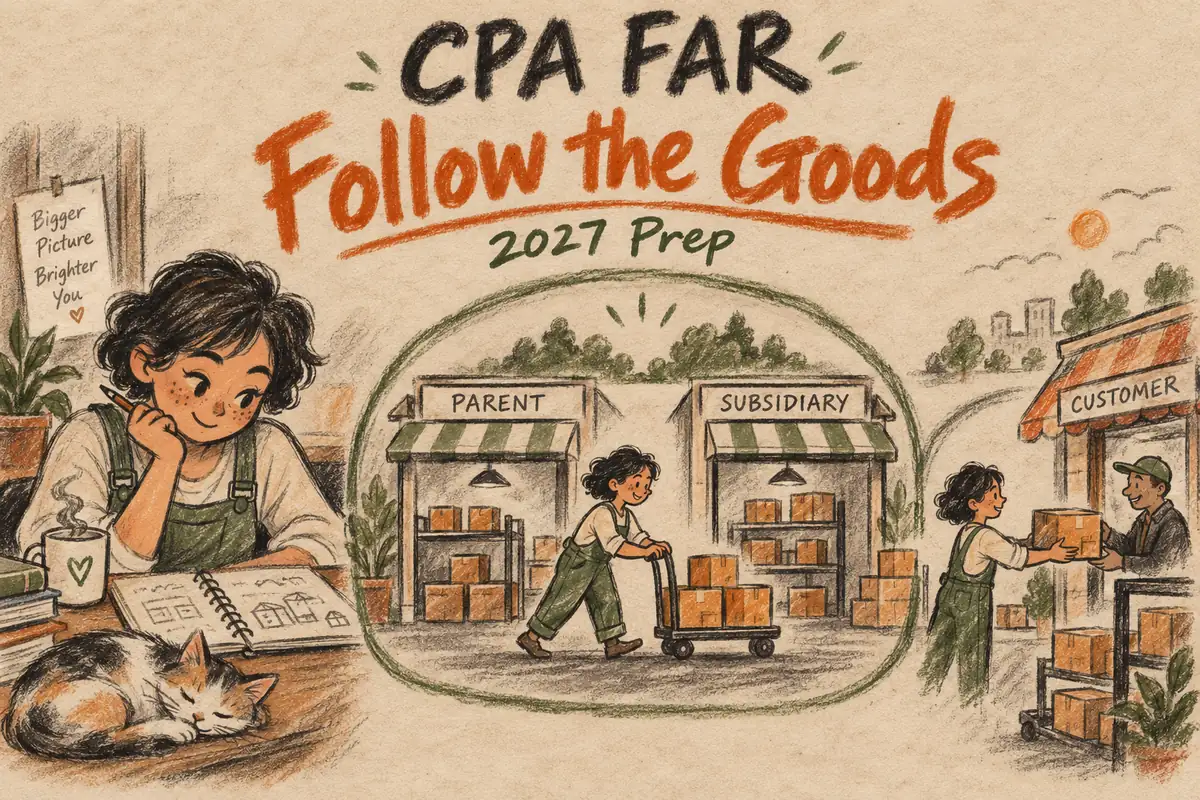
A parent sells 1,000 identical cases to its subsidiary, which resells 650 cases outside the group. At year-end, 350 remain on the subsidiary's shelf. Which amounts disappear when the two companies are consolidated?
Track the goods first. Remove the full internal sale. Then adjust for the profit embedded in the 350 unsold cases, whose transfer-price balance exceeds what the group paid its outside supplier. A remaining internal invoice balance is a third relationship to eliminate.
Our original fictional case follows those amounts from unit costs to six selected entries. It also covers a separate internal loan and accrued interest. We assume consolidation is already required and focus on intercompany eliminations, with acquisition accounting and investment-versus-equity elimination outside this illustration.
Define the group and the reporting layer
Pine owns all of Cove throughout the year. For this simplified US GAAP illustration, both are already included in the consolidated group and use the same reporting date, currency and perpetual inventory system.
Keep the example narrow. There is no opening intercompany inventory profit, inventory write-down, regulated-entity exception or tax effect in these pretax calculations. Fair-value acquisition adjustments, goodwill, noncontrolling interests and the parent's investment-account method are not modeled.
Deloitte's public consolidation discussion reproduces ASC 810-10-45-1 and explains eliminating internal balances, transactions and profit in assets still held within the group. We apply that principle to original figures, while the companies' separate records retain their own transactions.
Label the entry location. Each entry below belongs to the consolidation workpaper for the stated period. It does not instruct Pine or Cove to erase an actual customer invoice, supplier liability or loan from its standalone ledger.
Build a unit bridge before calculating a percentage
Pine purchases 1,000 identical cases from an outside supplier at $27 each, for a total group cost of $27,000. It transfers all of them to Cove at $45 each, recording a $45,000 internal sale and $27,000 cost of goods sold.
Cove sells 650 cases externally at $72 each. Its sales are $46,800, and its cost of goods sold is $29,250 using the $45 transfer price. The remaining 350 cases carry a $15,750 balance on Cove's books.
The group still owns those 350. Their original outside cost is $9,450, calculated as 350 times $27. The difference between their $15,750 transfer-price balance and $9,450 group cost is $6,300 of unrealized internal profit.
Check the physical quantities. The 650 sold cases plus 350 held cases account for all 1,000 transferred, with no returns, shrinkage or other movements in this dataset. Use the bridge below. It places the outside cost beside the internal transfer price for each set of cases, so you can see exactly which difference the inventory entry removes.
| Cases | Quantity | Group cost at $27 | Transfer value at $45 |
|---|---|---|---|
| Transferred internally | 1000 | 27000 | 45000 |
| Sold externally | 650 | 17550 | 29250 |
| Still held | 350 | 9450 | 15750 |
| Profit within still-held goods | 6300 |
Remove the full internal sale
The first inventory entry debits Sales $45,000 and credits Cost of Goods Sold $45,000. It removes the entire Pine-to-Cove sale from the combined revenue and cost figures, using this example's perpetual inventory accounts.
Use the complete transfer amount. Eliminating only the $15,750 related to unsold cases would leave $29,250 of internal sales in group revenue. Selling goods onward does not turn the earlier internal transfer into an external group sale.
This entry leaves combined gross profit unchanged. It reduces revenue and cost of goods sold by equal amounts, although their gross balances change. The separately calculated profit in unsold goods still needs to be removed.
Keep the amounts distinct. The $45,000 internal sale, $6,300 unsold profit and $9,000 unpaid invoice balance describe different relationships. One amount cannot replace the other simply because all three arose from the same transfer.
Remove only the profit remaining in inventory
Debit Cost of Goods Sold $6,300 and credit Inventory $6,300 for the second inventory entry. Cove's $15,750 ending inventory then becomes $9,450 at the consolidated group's outside cost.
This adjustment reduces pretax group profit. The goods are still inside. Pine recorded the $6,300 when it sold those cases to Cove, but no outside customer has bought them from the group by year-end. Profit attributable to the 650 externally sold cases remains in the group's results.
A percentage can confirm the amount. Pine's internal profit is $18,000 on its $45,000 sale, a 40% gross margin on transfer-price revenue. Apply 40% to the $15,750 remaining transfer-price inventory to obtain $6,300.
Do not substitute markup on cost. Dividing $18,000 by $27,000 gives two-thirds, or about 66.67%. That percentage measures profit against Pine's outside cost, whereas Cove's $15,750 inventory balance contains both that cost and the profit added on transfer. Multiplying the $15,750 transfer-price balance by two-thirds would wrongly remove $10,500 rather than $6,300.
Rebuild the external gross profit as a crosscheck
Before elimination, combined sales are $91,800 and combined cost of goods sold is $56,250. The inventory entries reduce sales by $45,000 and reduce cost of goods sold by a net $38,700.
Consolidated sales are therefore $46,800. Cost of goods sold becomes $17,550, equal to 650 externally sold cases times their $27 original group cost. Gross profit is $29,250, calculated as $46,800 minus $17,550.
Check that profit another way. Combined standalone gross profit is $35,550, and subtracting $6,300 of unsold internal profit leaves the same $29,250. Compare the two entries. The first reduces gross sales and cost equally, while the second reduces profit because $6,300 remains attached to goods sitting inside the group.
These are selected inventory results. They do not represent complete consolidated net income or a complete balance sheet, because this lesson does not supply every account and every required consolidation adjustment. Keep that boundary on any record you reuse.
Match the remaining invoice before eliminating balances
Cove has paid $36,000. The $45,000 transfer invoice therefore leaves a $9,000 receivable on Pine's books, matching the $9,000 payable that Cove still reports for the same invoice. Debit Accounts Payable $9,000 and credit Accounts Receivable $9,000 in consolidation.
Only the unpaid balance remains. Eliminating $45,000 from these closing balance-sheet accounts would remove more than either company still reports as outstanding. Earlier cash settlement has already reduced the receivable and payable on their separate books.
Suppose the records disagree. If Pine shows $9,000 but Cove shows $9,500 for the supposedly matching invoice, investigate the $500 difference before completing the elimination. Check the invoice, settlement date, cutoff and any separate charge instead of inventing a balancing amount.
No correction is assumed here. The worked dataset uses the matched $9,000 balances, and the mismatch is a separate diagnostic example with an unresolved cause. A standalone recording error, if established, would need its own correction before the consolidation workpaper uses the corrected balances.
Treat an internal loan and its interest as separate pairs
Pine also lends Cove $60,000 on July 1 at 6% simple annual interest. Assume a six-month accrual convention, no fees, no principal repayment and no interest payment before December 31. Both companies record $1,800 of accrued interest for the period.
Start with principal. Debit Notes Payable $60,000 and credit Notes Receivable $60,000 in the consolidation workpaper. The lender and borrower are both inside. From the group's perspective, this $60,000 creates neither a debt owed to an outside lender nor a receivable due from an outside borrower.
Next remove the income and expense. Debit Interest Income $1,800 and credit Interest Expense $1,800 to eliminate the internal interest recognized during the year. Their combined net effect is zero. Both amounts still need removal from the group's gross income and expense lines, even though leaving them together would not change this pair's net result.
The accrued balances still need attention. Debit Interest Payable $1,800 and credit Interest Receivable $1,800 for the unpaid interest. Removing the income and expense alone would leave an internal asset and liability in the selected consolidated balances.
Reconcile each pair independently. The $60,000 principal, $1,800 period interest and $1,800 unpaid interest have separate account roles, even though two amounts happen to match. Capitalized interest or a changed loan term would require facts beyond this illustration.
Check entry purpose as well as equal debits and credits
Add the six debit amounts. The $45,000 sale, $6,300 inventory adjustment, $9,000 invoice balance, $60,000 principal and two $1,800 interest entries total $123,900, matching the credits. That equality checks arithmetic, but it cannot tell you whether an entry removes the right account or the right amount.
Use the original inventory bridge. Ending inventory must be 350 cases at $27 group cost, giving $9,450. External sales must equal the 650 cases sold at $72, giving $46,800, and the selected internal receivable and payable must both become zero.
Then inspect the loan balances. Notes receivable, notes payable, interest receivable and interest payable should have no remaining amount from this specified internal loan. The interest income and expense should also have no remaining internal component.
Keep evidence beside each entry. An invoice supports the $9,000 balance pair, the inventory movement supports the $6,300 profit adjustment and the loan terms support $1,800 interest. A balanced journal entry cannot replace those source relationships.
Use the records without turning them into a universal entry list
Download the worked inventory bridge (CSV) for the original quantities, group costs, transfer prices and selected gross-profit reconciliation. The worked elimination entries (CSV) lists each debit and credit with its purpose, and the blank elimination record (CSV) leaves space for source evidence and the reporting layer.
Rebuild the next case from its facts. A different inventory system, opening profit deferral, impairment, tax effect or ownership structure may change the workpaper needed. This six-entry illustration does not establish a complete consolidation checklist for every company.
For additional study, the CPA FAR Online Center offers original FAR practice and feedback, while the AICPA exam-content page points to the blueprint effective for your testing date. Neither this lesson nor its records reproduce official questions, scoring or a licensing outcome prediction.
Before your next attempt, explain the $6,300 in units. Identify the 350 cases still inside the group and the $18 profit per case, then connect that amount to the inventory credit. That explanation lets you check the percentage instead of trusting it without a cost basis.
2027 preparation edition. Sources checked October 11, 2026. Pine, Cove, learner and all transactions are original fictional material. Selected pretax US GAAP intercompany workpaper entries for a wholly owned group with consolidation assumed. Same date/currency and perpetual inventory. No opening internal inventory profit, impairment, regulated exception or tax effects. Acquisition accounting, investment/equity elimination and full financial statements are outside this lesson. Cover is conceptual art.

Related to This Article
More math articles
- Unlock the Answers: “GED Math for Beginners” Solution Manual
- How to Find The Derivative of A Function
- How to Prepare for the ParaPro Math Test?
- Electron Transport and Chemiosmosis: How ATP Forms
- The Ultimate TASC Math Formula Cheat Sheet
- Top 10 Tips to Create an ASTB Math Study Plan
- How to Multiply Matrix? (+FREE Worksheet!)
- How to Multiply and Divide Complex Numbers? (+FREE Worksheet!)
- How to Write an Equation from a Graph?
- Rocks and the Rock Cycle


What people say about "CPA FAR Consolidations: Identify Elimination Entries (2027 Prep)"?
No one replied yet.