AP Business with Personal Finance: Read a Cash-Flow Statement (2027 Prep)
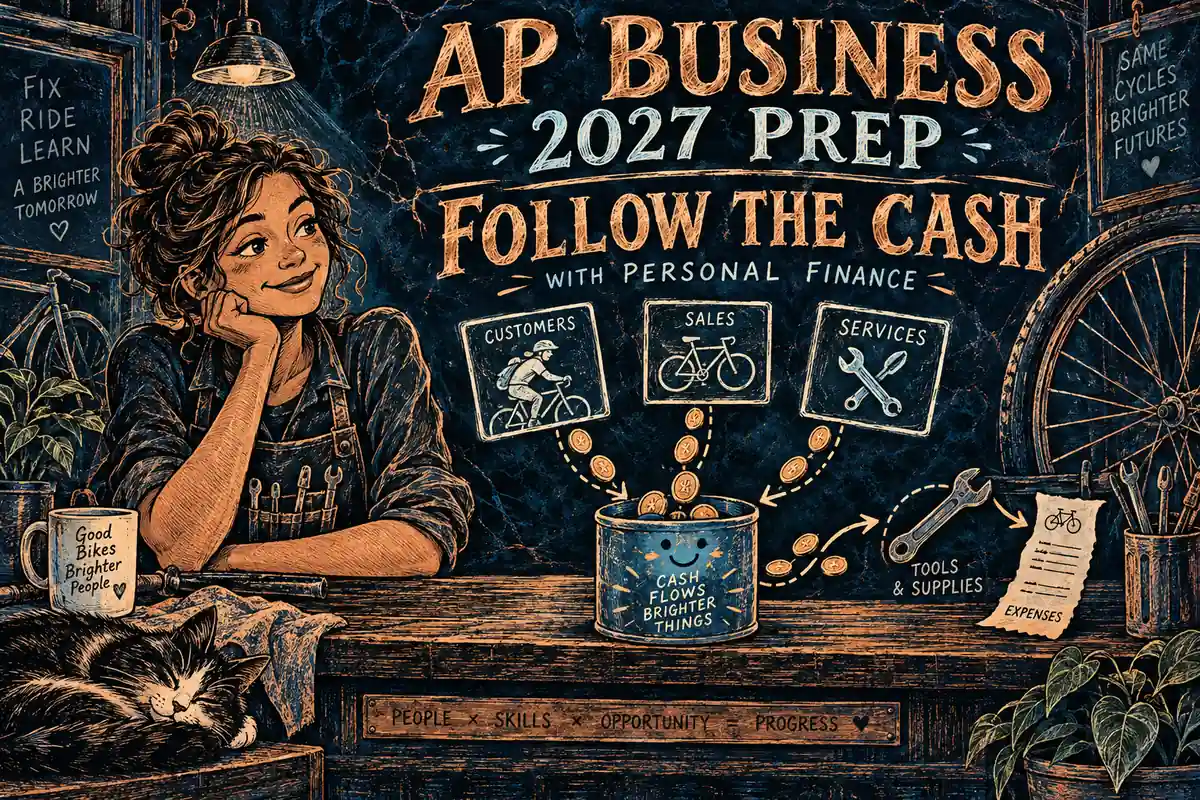
A bicycle repair shop reports $460 in profit for the month, but its cash balance rises by only $200. Neither figure has to be wrong. Some completed work remains unpaid, equipment used cash, and the owner and a lender supplied money that was not sales revenue.
Follow the transactions. To read a cash-flow statement, separate receipts and payments by their purpose, calculate the net change and add that change to the opening cash balance. Then compare the result with profit without treating the two measures as interchangeable.
This original AP Business with Personal Finance example keeps one small shop's numbers together from start to finish. You will trace its $800 closing cash balance and explain why that balance, the $200 increase and the $460 profit answer different questions.
Connect the example to Topic 3.8
College Board's current AP Business with Personal Finance course and exam description places cash-flow statements in Topic 3.8. Learning objective 3.8.A concerns their components, while 3.8.B concerns how stakeholders use the information, including the ability to meet obligations when profit and cash differ.
The worked shop is fictional. Its three-category presentation and short profit reconciliation are teaching aids for reading financial information, rather than a claim that every accounting detail below is a separate AP requirement.
Use the AP Business with Personal Finance Online Center to organize wider course review. Here, keep the reporting period fixed at one month and ask whether each listed event actually moved cash during that month.
Set the assumptions before adding the amounts
The shop starts the month with $600 in unrestricted cash, with no cash equivalents, foreign-currency transactions or transfers between its own cash accounts in this simplified example. Opening accounts receivable are zero.
During the month, it completes $1,200 of repair services. Customers pay $900 for that work during the month, and the remaining $300 is billed on credit and still unpaid at month-end. All services are completed, with no customer deposits or unearned revenue.
The shop pays $700 for this month's ordinary operating expenses, all recognized in the same month. There are no inventory purchases, prepayments, unpaid operating expenses or other working-capital changes in the model.
Equipment costs $800 in cash. The owner contributes another $400 in cash, a lender advances $500, and the shop repays $100 of loan principal. These are separate transactions, with the loan received as cash and the equipment paid for in cash.
For the profit comparison, total depreciation expense for the month is a supplied $40, with no calculation based on an assumed useful life required here. No interest, taxes, owner withdrawals or other transactions are included in this deliberately limited teaching period.
Read the operating receipts and payments
The shop collects $900 from completed repairs and pays $700 of current operating expenses. Those are the modeled cash movements from ordinary operations, giving operating cash flow of $900 – $700 = $200.
Leave the unpaid $300 out. The completed work contributes to this month's revenue under the example's accrual accounting, but the uncollected invoice has not produced a cash receipt. Its amount becomes closing accounts receivable instead.
The opening $600 is also excluded from operating receipts. It is cash already present at the start, and adding it as new customer money would count an existing balance as a current-period flow.
The SEC beginner guide to financial statements explains the distinction between profit and cash, including adjustments for noncash items and changes in operating assets or liabilities. Our shop's direct receipts-and-payments presentation makes those cash movements visible before the later profit reconciliation.
Keep equipment purchases in their own category
The $800 equipment payment is an investing outflow in this example because the shop bought an asset for continuing use in its work. It is not a payment for repairs sold to customers or an infusion of funding.
Use the transaction's purpose. An equipment purchase can use cash even though its entire price is not recognized as an ordinary expense in that month's profit calculation. Here, the supplied depreciation expense represents the month's recognized equipment cost allocation.
Do not subtract $40 again. Depreciation reduces this example's profit, but it is not an additional current-month cash payment on top of the $800 equipment purchase. Treating both as cash outflows would overstate cash used by $40.
The OpenStax cash-flow classification guidance provides a reference for the operating, investing and financing categories. The shop uses uncomplicated cash transactions so classification can be checked without introducing a noncash equipment acquisition or a sale of an existing asset.
Separate funding from customer revenue
The owner's $400 contribution and the lender's $500 advance are financing inflows. The $100 principal repayment is a financing outflow, giving net financing cash flow of $400 + $500 – $100 = $800.
Borrowing is not a sale. The loan increases cash while also creating a repayment obligation, and an owner contribution increases invested capital rather than revenue earned from repairs. Neither belongs in this month's $1,200 service revenue.
Principal is separate from interest. The model includes only the $100 return of borrowed principal and no interest charge, so the whole listed repayment reduces debt rather than profit. If a real payment contains both, its components need separate treatment under the applicable reporting rules.
A positive cash change can therefore reflect funding as well as customer activity. Check the financing section before describing a higher balance as evidence that the shop generated that entire amount from its services.
Reconcile the statement to closing cash
Add the category totals. Operating provides $200, investing uses $800 and financing provides $800, giving a net cash increase of $200 – $800 + $800 = $200.
Now use opening cash. The shop's closing balance is $600 + $200 = $800. The $600 beginning balance and $800 ending balance are amounts held at different dates, while the $200 increase describes movement over the month.
Cross-check the receipts and payments. Cash receipts total $900 + $400 + $500 = $1,800, and cash payments total $700 + $800 + $100 = $1,600. Their $200 difference matches the sum of the three category totals.
The table keeps these amounts visible. Download the worked shop ledger (CSV) to inspect every modeled transaction, including the unpaid service revenue and depreciation, whose current-month cash amounts are zero.
| Line | Amount (USD) | Meaning |
|---|---|---|
| Opening cash | 600 | Balance at beginning |
| Operating cash flow | +200 | 900 receipts less 700 payments |
| Investing cash flow | -800 | Cash equipment purchase |
| Financing cash flow | +800 | 400 owner + 500 loan – 100 principal |
| Net cash change | +200 | 200 – 800 + 800 |
| Closing cash | 800 | 600 beginning + 200 increase |
Explain the difference from the $460 profit
Under the stated accrual assumptions, revenue is $1,200 and recognized expenses are $700 plus $40 depreciation. Profit is therefore $1,200 – $700 – $40 = $460.
Reconcile operating cash only. Starting from $460 profit, add back the $40 noncash depreciation and subtract the $300 increase in accounts receivable. That gives $460 + $40 – $300 = $200 operating cash flow.
The add-back does not create money. It reverses a noncash expense already deducted in profit so that this reconciliation can reach the cash measure. The $800 equipment payment remains in investing, outside that operating calculation.
After that operating reconciliation, include investing of -$800 and financing of +$800 to recover the total $200 cash increase. In this particular month they offset, making operating cash flow and total cash change numerically equal even though the measures are conceptually different.
The closing $800 is not profit. It contains opening cash and the net effect of all modeled receipts and payments, while profit measures this month's earned revenue less recognized expenses.
Interpret the result without inventing a forecast
The shop generated $200 in operating cash this month and used $800 for equipment, with net financing supplying another $800. That explains the ending balance and shows why reviewing only the final positive number would hide the source of funding.
Future months remain unknown. One month's figures cannot establish that repairs will keep generating cash, that the equipment will earn an adequate return or that customers will pay every outstanding invoice. The example supplies no forecast or loan repayment schedule.
Check payment dates separately. A positive month-end balance does not establish that enough cash was available on every earlier day, because these monthly totals do not show the order of receipts and payments.
For a lender assessing a real business, future obligations, collection timing and other evidence would matter alongside the historical statement. This teaching case supports an explanation of the past month's flows, without recommending borrowing or an equipment purchase.
Use a repeatable reading check
Confirm the period and opening cash first. Read each transaction's description, identify whether cash moved and assign any cash movement to its appropriate category. A completed credit sale still awaiting collection should not become a cash receipt through relabeling.
Recalculate the totals. Verify that opening cash plus the net change equals closing cash, then compare profit with operating cash using only adjustments supported by the supplied facts.
The blank cash-flow reading record (CSV) leaves room for a transaction's evidence, cash amount, category, reason and effect on the profit comparison. Keep a zero-cash item visible in your notes when it explains a difference, rather than quietly dropping it from the reasoning.
Continue through the AP Business with Personal Finance Online Center for broader preparation. For this shop, finish by tracing the $300 unpaid invoice into both the revenue calculation and the operating-cash reconciliation, then check that it never appears among the month's cash receipts.
2027 preparation edition. Current College Board framework, SEC explanation and OpenStax category guidance checked October 11, 2026. Shop, amounts, assumptions, worked ledger and reconciliation are original fictional teaching material, not official exam questions, a full real-company financial report or personalized financial advice. No daily cash chronology or forecast is supplied.

Related to This Article
More math articles
- Maryland Algebra 1 Free Worksheets: 65 Free Printable Algebra 1 Worksheets with Worked Answers
- Unfunded mandates
- Taylor and Maclaurin Series Calculator (Free)
- Electron Transport and Chemiosmosis
- Fibonacci Calculator — nth Number & Sequence
- Reading Clocks
- The Ohio OST Grade 3 Math Worksheet Pack — 49 Free Printable Pages with Solutions
- Free Grade 7 English Worksheets for Georgia Students
- How to Graph the Cosine Function?
- Comparing and Ordering Numbers for 5th Grade: Tips and Practice


What people say about "AP Business with Personal Finance: Read a Cash-Flow Statement (2027 Prep)"?
No one replied yet.