What you will be able to do
calculate a fictional insured loss under stated terms; compare saving, insurance, and investing by purpose and risk; analyze diversification, real return, fees, fraud signs, documentation, and remedies
How do insurance, investing, diversification, fees, inflation, verification, and consumer law address different risks?
calculate a fictional insured loss under stated terms; compare saving, insurance, and investing by purpose and risk; analyze diversification, real return, fees, fraud signs, documentation, and remedies
Explain why an insurance premium purchases conditional risk protection rather than accumulating in a personal account that can always be withdrawn
Risk pooling works when many policyholders pay predictable premiums so covered losses for some can be financed. A policy is a contract defining people or property, covered events, dates, deductibles, copays or coinsurance, limits, exclusions, valuation, claim evidence, and appeal. Insurance reduces specified financial consequences; it does not prevent the event or promise that every submitted loss qualifies. A lower premium may accompany a higher deductible, narrower network, lower limit, or broader exclusions. Comparing price without protection can create false savings. The policyholder also considers whether the deductible is realistically affordable and whether the insurer and seller are authorized. Insurance is not investing: its primary benefit is transferring low-frequency or severe risk, even in a year with no claim. Regulatory rules and coverage terms change by product and jurisdiction, so real decisions require current qualified guidance
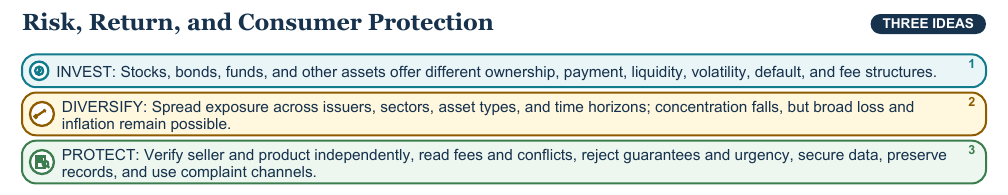
A stock is an ownership claim; a bond is a debt obligation; a pooled fund holds a collection of assets under stated rules. Diversification can reduce company-specific or sector-specific risk, but it cannot eliminate market decline, interest-rate change, inflation, fraud, or fees. Time horizon and liquidity matter because selling during a decline can lock in loss. Nominal return measures dollar growth; real return adjusts for changing purchasing power. A 6 percent nominal gain with 3 percent inflation is roughly a 3 percent real gain before taxes and fees, using an approximation. Small annual fees compound into meaningful differences over long periods, so disclosures and conflicts matter. Consumers verify registration or authorization where relevant, identify whether advice carries a fiduciary duty in that relationship, and document receipts, terms, messages, dates, and requested remedy. Complaints should follow official seller, regulator, or dispute channels with trusted adult support—not public exposure of private data
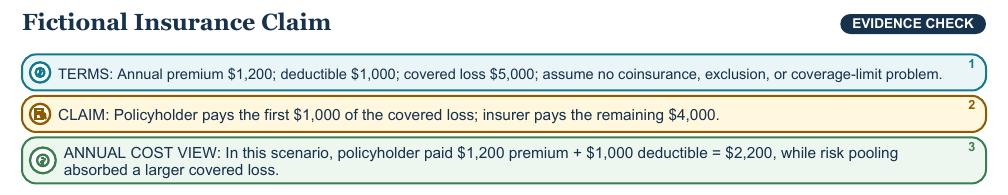
First verify covered event, exclusions, valuation, limit, dates, and claimant; then apply deductible and other cost-sharing in contract order
Insurance answers ‘which loss is transferred?’; investing answers ‘which risk is accepted for possible return?’; saving answers ‘how accessible and stable are funds?’
Diversification reduces concentration risk, not every market, inflation, fee, liquidity, credit, or fraud risk
Use complete fictional terms to calculate one claim, compare coverage, estimate nominal and real return, identify concentration and fees, and write a consumer-remedy record
Insurance pools and transfers specified losses under contract terms; investing accepts uncertainty for possible return. Sound consumer decisions compare coverage, diversification, real return, fees, conflicts, verification, records, and remedies
Work through all 12 questions. Open an answer only after you have written or explained your response.
$4,000
$1,000
$2,200
An excluded, uncovered, out-of-date, or over-limit loss changes or prevents payment, so cost-sharing applies only after eligibility is established
It may include a higher deductible, lower limit, narrower coverage, broader exclusions, or greater out-of-pocket cost
A stock generally represents ownership; a bond represents an issuer’s debt obligation under stated payment terms
It spreads issuer or sector exposure, but broad market, inflation, interest-rate, liquidity, credit, fee, and fraud risks remain
About 3 percent using the simple approximation of nominal return minus inflation
Accept a complete product-specific audit that separates possible gain, plausible loss, and disclosed cost or incentive
The fee is removed repeatedly and also reduces the base that could earn future compound returns
Guaranteed exceptional return, pressure, secrecy, unclear fees, unverified seller, credential requests, fake endorsements, or inability to explain the product; any four
Receipt, contract, disclosure, warranty, messages, dates, screenshots, transaction record, tracking, seller identity, or requested remedy; any four