What you will be able to do
calculate total repayment and borrowing cost; distinguish installment, revolving, secured, and cosigned credit; interpret APR, compounding, amortization, credit reporting, and deceptive warning signs cautiously
How can a borrower compare credit contracts by total cost, APR, term, repayment structure, rights, and downside risk?
calculate total repayment and borrowing cost; distinguish installment, revolving, secured, and cosigned credit; interpret APR, compounding, amortization, credit reporting, and deceptive warning signs cautiously
Explain why two offers for the same principal can have different total costs even when the lower-cost offer has the larger monthly payment
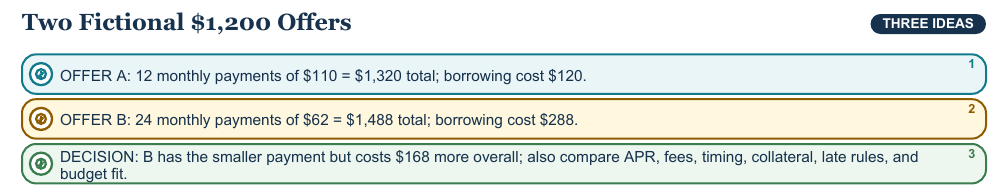
Principal, interest, fees, term, and payment schedule determine borrowing cost. Total repayment equals all required payments and upfront or recurring fees; subtracting principal gives total borrowing cost. APR annualizes covered cost for comparison, but borrowers still need total dollars because term length and behavior differ. Promotional or variable rates require the date and trigger for change. Amortized installment payments often pay more interest early because interest is calculated on a larger outstanding balance. Revolving accounts change with purchases, payments, fees, and interest, so minimum-payment examples require explicit assumptions. Simple-interest classroom formulas should not be projected onto contracts using daily balance or compounding. A complete cost table names formula, rate type, fees, term, payment dates, prepayment rule, and consequences of one missed payment
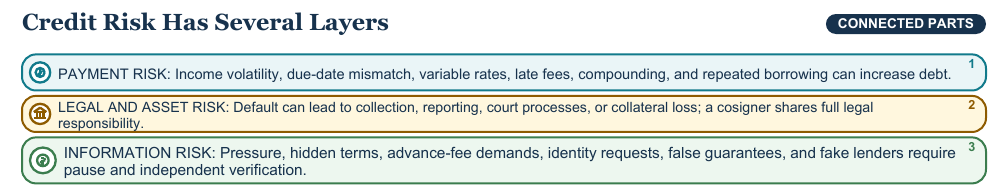
Credit reports can contain account history, balances, payment status, and inquiries; scoring models summarize selected data differently. Reports can be incomplete or wrong and reflect unequal access to mainstream credit. A score does not measure honesty, intelligence, wealth, or future certainty. Checking an authorized report for errors is different from sharing it publicly, and disputes follow current legal procedures. Secured credit can lower lender risk while putting collateral at risk. A cosigner is responsible for repayment and may face credit or collection consequences. High-cost lending can exploit urgency, repeated renewal, automatic account access, and unaffordable terms. Consumers should use independently verified providers, preserve complete disclosures, avoid blank documents and pressure, and seek a trusted adult or qualified nonprofit resource. Alternatives—waiting, saving, lower-cost assistance, negotiation, or a smaller purchase—have their own costs but belong in the comparison
Total every payment and fee, subtract principal, then inspect APR, rate changes, collateral, reporting, default, dispute, and hardship terms
After the base calculation, apply the contract’s exact late fee, rate, reporting, collateral, and timing rules; never invent missing terms
It summarizes selected reported data for a stated model and purpose; it does not measure moral worth or complete financial health
Compare Offers A and B with a third secured offer. Calculate total cost, test one missed payment using printed terms, identify rights and red flags, and state the least-supported assumption
Credit analysis joins total repayment, APR, term, amortization, cash-flow fit, collateral, reporting, rights, and fraud risk. Records and scores are limited tools, never measures of personal worth
Work through all 12 questions. Open an answer only after you have written or explained your response.
$1,320
$120
$1,488
$288
$168
Offers with different terms, fees, and behavior can have different total dollars even when annualized rates aid comparison
Scheduled repayment dividing payments between interest and principal over a term
Contracts may use daily balance, compounding, variable rates, amortization, and fees; the disclosed method controls
Accept an accurate base calculation plus contract-specific consequences; unknown terms must be labeled unknown
Full legal responsibility to repay if required, with possible reporting and collection effects
Reporting systems receive selected data from furnishers; identity matching, timing, omission, and disputes can create inaccuracies or gaps
Pressure, guaranteed approval, advance fees, blank documents, hidden terms, credential requests, remote access, fake contact, or secrecy; any four