What you will be able to do
build and stress-test a cash-flow budget; interpret APY, compounding, liquidity, inflation, and saving goals; compare banking terms, reconcile transactions, and apply fraud protections
How can a person build a resilient budget, evaluate saving growth, and use financial accounts securely?
build and stress-test a cash-flow budget; interpret APY, compounding, liquidity, inflation, and saving goals; compare banking terms, reconcile transactions, and apply fraud protections
Explain why an annual insurance bill belongs in a monthly plan even though it is not due in most months
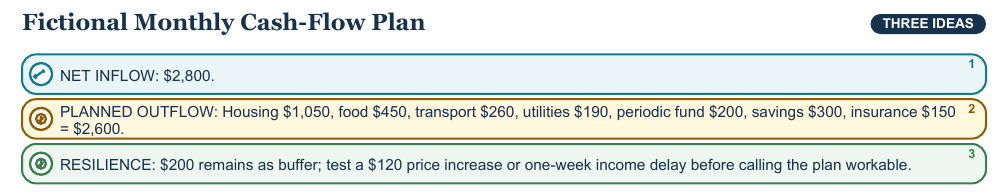
Cash-flow planning begins with net income, deposit dates, bill dates, minimum obligations, essential variable costs, periodic expenses, and goals. Fixed, variable, and periodic describe predictability, not importance. A sinking fund converts a known future expense into smaller regular amounts. A buffer covers estimation error; an emergency reserve addresses larger unplanned disruptions, though building one may take time. Stress-testing changes one assumption at a time: reduced hours, delayed deposit, price increase, medical cost, or transportation repair. If necessities exceed income, the plan has a resource gap, not a moral failure. Options can include benefit eligibility, fee negotiation, payment timing, legitimate income, shared resources, or qualified counseling. A budget should never depend on impossible cuts to food, health, safety, or housing simply to make arithmetic look balanced
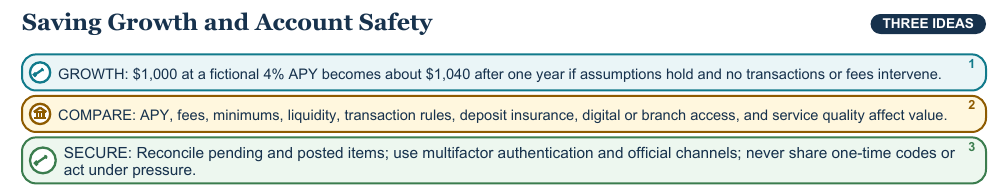
Compound interest credits return on earlier interest as well as principal. APY supports one-year deposit comparison when institutions use different compounding schedules, but a promotional yield may change and fees can erase growth. Inflation-adjusted, or real, growth depends on how prices change. Money needed soon usually requires liquidity and stability; a longer-term goal may tolerate different restrictions or risks. Banks and credit unions offer varied ownership structures and government-backed deposit insurance for eligible accounts at covered institutions up to legal limits. Insurance does not cover every payment app, investment, cryptocurrency, scam transfer, or credential theft. Account holders compare fee schedules, minimums, overdraft settings, hold periods, interest, and dispute processes. Reconciliation separates pending from posted transactions and can detect error or fraud. Security means unique credentials, multifactor protection, alerts, device updates, independent callback through an official number, and immediate reporting—not secrecy from trusted support
A month ending above zero can still trigger fees if a payment occurs before the income needed to cover it
Align pay dates, obligation dates, and saving or periodic-fund transfers; then mark the lowest projected daily balance
It describes effective annual yield under stated conditions; variable rates, fees, withdrawals, and changing terms alter actual growth
Apply two shocks to the fictional $2,800 plan, then compare three fictional accounts for one emergency and one long-term goal using APY, fees, liquidity, insurance, and access
Resilient budgeting aligns amounts and dates, plans periodic costs, protects necessities, and tests shocks. Saving and banking decisions balance APY, inflation, liquidity, fees, insurance, reconciliation, and security
Work through all 12 questions. Open an answer only after you have written or explained your response.
$2,600
$200
$80
A sinking fund prepares for a known future cost; an emergency reserve covers significant unplanned needs
A bill may arrive before the corresponding income, and pending transactions or holds can reduce available balance
Income delay or loss, price increase, repair, medical cost, annual bill, fee, or inaccurate estimate; any four
About $1,040 under the stated no-fee, no-transaction assumption
Fees are withdrawals from the account and can exceed some or all interest credited
Accept a complete comparison that distinguishes effective yield and fees, usable access, and verified coverage or security
The user’s transaction record and receipts with posted and pending entries in the institution’s record
Examples include investment losses, crypto assets, safe-deposit-box contents, and balances not held in an eligible insured deposit account—including many nonbank payment-app balances; any three. Deposit insurance protects against failure of the covered institution, not scam transfers or credential theft
Unique passwords, multifactor authentication, alerts, official contact channels, no shared codes, updates, reconciliation, or immediate reporting; any four