What you will be able to do
distinguish major taxes, rates, and incidence; classify public, private, club, and common-pool goods; analyze a public budget through authority, revenue, trade-offs, deficit or surplus, distribution, and long-term effects
How do governments raise and allocate resources, why are public goods difficult to finance privately, and how should tax and budget choices be evaluated?
distinguish major taxes, rates, and incidence; classify public, private, club, and common-pool goods; analyze a public budget through authority, revenue, trade-offs, deficit or surplus, distribution, and long-term effects
A town needs flood warnings that benefit everyone, including people who do not pay voluntarily. Explain why private collection may fall short and name one public decision needed
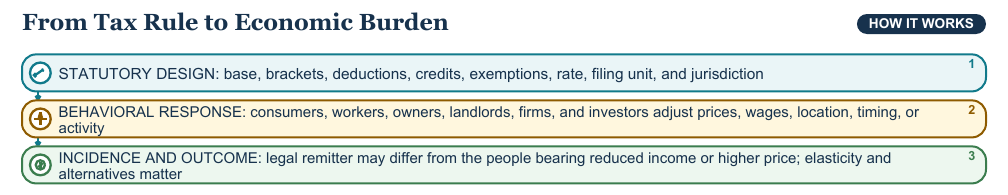
Governments use individual and corporate income taxes, payroll taxes, sales and excise taxes, property taxes, fees, tariffs, and other revenues. A progressive tax takes a larger share of income as income rises; proportional takes a constant share; regressive takes a smaller share, though the conclusion depends on which taxes, transfers, time period, and income measure are included. Sales taxes often burden lower-income households more heavily as a share of income, while exemptions or credits can change that pattern. A marginal rate applies only to the next dollars in its bracket, not to all income. The effective rate divides total tax by the tax base. Statutory incidence identifies who sends payment; economic incidence asks who ultimately loses purchasing power through prices, wages, profit, or returns. A tax on a firm can be shared among owners, workers, and consumers depending on competition and responsiveness. Evaluation considers revenue, fairness, simplicity, compliance, administration, incentives, avoidance, volatility, and how funds are used
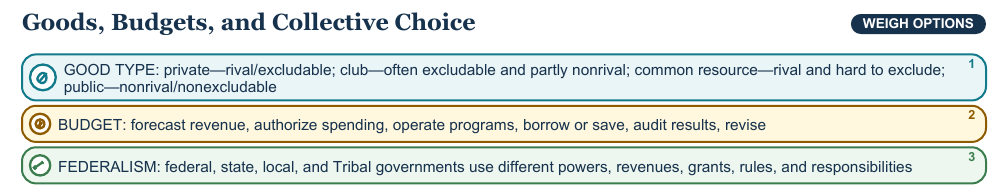
Nonrival use means one person’s benefit does not greatly reduce another’s; nonexcludability makes it difficult to keep nonpayers out. National defense and some public information approximate public goods, producing free-rider problems. A fishery is instead a common-pool resource: exclusion is difficult but one person’s catch reduces what remains. A toll road with spare capacity resembles a club good; food is private. Classifying correctly helps select taxes, fees, regulation, property rules, public provision, or collective management. A public budget plans or forecasts revenue and spending. Legal authority to spend comes from applicable appropriations or other enacted law; for example, a federal budget resolution establishes a fiscal blueprint but does not itself authorize spending. Federal mandatory programs generally follow eligibility or formula law, discretionary programs depend on annual appropriations, and interest follows debt obligations. State balanced-budget rules and local revenue powers vary. A deficit is a one-period flow; debt is an accumulated stock, so they are not interchangeable. Borrowing can finance emergencies or long-lived investment and support demand, but persistent debt can raise interest cost and reduce future flexibility. Good budget analysis tests forecast uncertainty, opportunity cost, legal duty, maintenance, distribution, fiscal federalism, transparency, and measurable outcomes rather than treating a government budget as identical to a household checkbook
State tax base, bracket, total liability, marginal rate, effective rate, affected behavior, and transfer or spending context before judging burden
List jurisdiction, authority, revenue base, grant or borrowing, appropriation, beneficiary, burden bearer, timeline, uncertainty, audit, and outcome measure
It specifically concerns nonrivalry and nonexcludability; schools, health care, parks, and roads have mixed characteristics and policy reasons
Balance a 100-unit revenue forecast across safety, library, transit, flood warnings, debt service, and reserves, then explain tax incidence, public-good logic, trade-offs, equity, and risk
Taxes differ by base, rate, and incidence; public-good characteristics create collective-finance problems; budgets translate forecasts and priorities into authorized spending, deficits or surpluses, debt, and distributive choices
Work through all 12 questions. Open an answer only after you have written or explained your response.
Tax is $1,000 plus $2,000, or $3,000; marginal rate is 20 percent; effective rate is $3,000 divided by $20,000, or 15 percent
Brackets apply marginal rates only to income within each bracket, so the first $10,000 remains taxed at 10 percent
Statutory incidence identifies who legally remits payment; economic incidence identifies whose real income ultimately falls after prices, wages, profits, and behavior adjust
Answers vary; a strong answer names purchases as base, retailer as remitter, consumers or others as possible bearers, a plausible change, and an exemption, credit, or transfer as adjustment
Nonrival and nonexcludable
A common-pool resource: excluding users can be difficult, while each catch reduces the stock available to others
A club good: tolling makes exclusion possible, and one additional user may impose little rivalry until congestion
People can benefit without paying, so voluntary contributors may not capture enough benefit to finance the socially desired quantity
Outlays total 105, producing a deficit of 5 units
A deficit is the gap between outlays and revenue during a period; debt is accumulated outstanding borrowing shaped by past deficits, surpluses, and interest
A bridge provides services over many years, so spreading cost can align payers and beneficiaries, but both investment and routine borrowing require cost, benefit, risk, maintenance, interest, and fiscal-space analysis
A complete response addresses all ten elements and makes an explicit, measurable trade-off rather than claiming every service can expand without cost