Work through all 12 questions. Open an answer only after you have written or explained your response.
1. Which statement best captures the lesson’s central conclusion about Credit, Insurance, Investing, and Consumer Protection? A. Responsible financial decisions compare credit’s total obligation, insurance coverage and exclusions, investment risk and diversification, privacy, fraud signals, alternatives, and enforceable consumer protections. B. Credit, Insurance, Investing, and Consumer Protection can be explained by one timeless factor, so context and contrary evidence are unnecessary. C. One example proves the same pattern for every society, place, and period
Check answer
Responsible financial decisions compare credit’s total obligation, insurance coverage and exclusions, investment risk and diversification, privacy, fraud signals, alternatives, and enforceable consumer protections
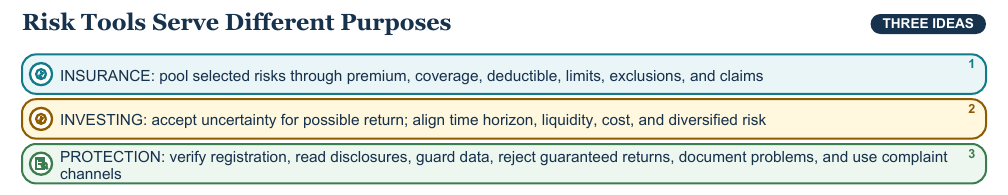
2. Policy X costs 240 units per year with a 1,000-unit deductible and excludes flood loss; Policy Y costs 360 with a 500-unit deductible and includes flood under stated limits. A consumer’s main concern is flood. Which comparison is responsible? A. Policy Y addresses the named risk, but the consumer must still compare limits, definitions, exclusions, claim rules, total cost, and ability to pay the deductible B. Policy X is automatically better because its premium is lower even though it excludes the named risk C. Policy Y guarantees payment for every possible flood loss because its summary says flood is included
Check answer
Policy Y addresses the named risk, but the consumer must still compare limits, definitions, exclusions, claim rules, total cost, and ability to pay the deductible
3. An adviser says, ‘I am acting as a fiduciary for this account,’ charges a 1 percent asset fee, and may receive referral payments. What should the consumer verify? A. the adviser’s legally defined role and registration, written fiduciary obligation, total compensation, referral conflicts, services, and disciplinary record B. only whether the adviser’s advertisement uses the word trusted in large print C. nothing else, because saying fiduciary removes every possible fee, conflict, or limit
Check answer
the adviser’s legally defined role and registration, written fiduciary obligation, total compensation, referral conflicts, services, and disciplinary record
4. Draw a three-branch decision tree for borrow, insure, or invest, with contract terms, risk questions, official verification, privacy check, alternative, and stop conditions
Check answer
Each branch should ask the tool’s purpose, total cost or coverage, risk, time, liquidity, fees, exclusions, identity verification, and alternatives. A stop branch should flag pressure, secrecy, or guaranteed returns
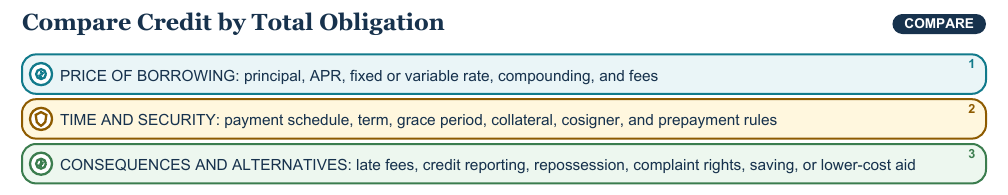
5. Explain both terms in this lesson’s context: credit and principal
Check answer
credit: the ability to borrow now and repay under agreed terms. principal: the original amount borrowed or invested. A complete response connects each definition to this topic
6. Compare APR with total repayment. Why does a consumer need both?
Check answer
APR standardizes annual borrowing cost for comparison; total repayment shows dollars paid over the actual amount and term. Term, fees, payment timing, and early payoff can change total dollars
7. Fact card: Fictional one-year loans for 500 units: Loan A charges 10 percent simple interest plus a 20-unit fee; Loan B charges 18 percent simple interest and no fee. Both require one payment at year end. Calculate each total borrowing cost and choose the lower-cost loan under these exact terms
Check answer
Loan A costs 50 units interest plus 20 fee, or 70 total. Loan B costs 90 units. Under these exact terms, Loan A has the lower borrowing cost; real comparisons also require contract and risk review
8. Use the fictional 500-unit loans to prepare a decision record that includes cost and contract risk, not just the advertised rate
Check answer
Loan A costs 70 units: 50 interest plus a 20-unit fee, for 570 total repayment. Loan B costs 90 units, for 590 total repayment. Under the stated one-year terms A costs less, but a decision should still compare payment timing, late terms, security, remedies, lender legitimacy, disclosures, and complaint rights
9. Explain why choosing a higher insurance deductible may lower premium but increase financial risk after a covered loss
Check answer
The policyholder agrees to absorb more of each covered loss before insurance pays, reducing the insurer’s expected payment and often the premium. The household must be able to pay the deductible
10. How might a borrower, lender, insurer, policyholder, investor, regulator, and scammer view disclosure and verification differently?
Check answer
Legitimate parties need accurate risk and enforceable terms; regulators protect fair dealing; a scammer benefits from urgency, confusion, secrecy, and weak verification. Interests are unequal, so official checks matter
11. A message promises a guaranteed 20 percent monthly return if payment is sent today in cryptocurrency. Give four response steps
Check answer
Do not pay or share data; pause and preserve the message; verify the person and product through official regulators independently; discuss with a trusted adult or qualified professional; report the suspected scam through an official channel
12. Answer the essential question—How can consumers compare financial tools, manage risk, and recognize protections and harmful practices?—with a claim, at least two specific details, and one limitation or qualification
Check answer
Answers vary. A defensible response should explain that responsible financial decisions compare credit’s total obligation, insurance coverage and exclusions, investment risk and diversification, privacy, fraud signals, alternatives, and enforceable consumer protections. It should use at least two lesson details, distinguish evidence from inference, and qualify the claim by period, region, perspective, or available evidence