What you will be able to do
classify fixed, variable, and periodic expenses; balance and revise a fictional budget; compare transaction and savings services using fees, access, insurance, interest, and security
How can a budget, saving plan, and secure banking practices help a person manage changing cash flow and goals?
classify fixed, variable, and periodic expenses; balance and revise a fictional budget; compare transaction and savings services using fees, access, insurance, interest, and security
Explain why an annual $600 expense should be planned as roughly $50 per month even though no payment occurs in most months
A useful budget begins with net income and the timing of deposits. Expenses can be fixed, variable, or periodic, but categories describe predictability rather than importance. Food or medicine can be necessary and variable. A yearly fee becomes a monthly sinking-fund amount so that one due date does not create a surprise. A buffer acknowledges estimation error and irregular events. Budgeting is not punishment and does not solve insufficient income by itself. If required costs exceed income, arithmetic reveals a structural gap; options may include adjusting timing or choices, increasing income where feasible, using eligible assistance, negotiating bills, or seeking qualified help. No lesson should imply that every hardship results from careless spending. Plans are revised when income, price, household need, or goals change
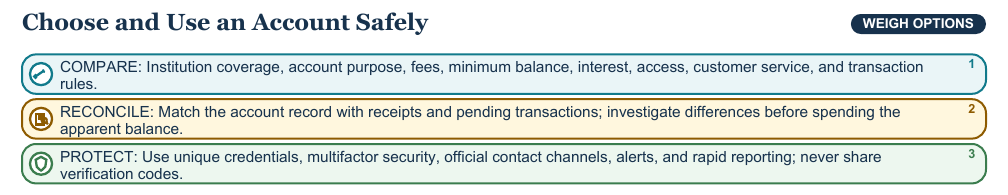
Checking accounts support frequent payments. Savings accounts are designed for reserves and may pay interest. A bank or credit union may set withdrawal limits or fees in its current account agreement, so compare the institution’s actual terms. Banks and credit unions differ in ownership and insurance systems, but eligible deposits at covered institutions receive government-backed protection up to legal limits. Deposit insurance does not protect investment losses, stolen credentials, every payment app balance, or money sent voluntarily to a scammer. Account comparison includes monthly and transaction fees, overdraft policy, minimums, branch or digital access, interest, and customer support. A posted balance may not reflect pending transactions. Reconciliation compares the institution’s record with the user’s own record and receipts. Fraud prevention includes verifying the institution through official channels, pausing when pressured, protecting personal information, and reporting suspicious activity promptly to a trusted adult and the provider. Saving can be automated, but flexibility matters when needs change
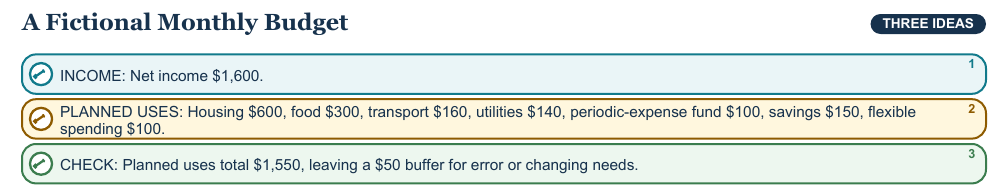
Match each amount to a period, include periodic costs and a buffer, and revise without moral judgment when conditions change
Place income dates, bill dates, periodic funds, savings transfer, and buffer on one timeline to detect timing shortages
Arithmetic can balance only after needs are reduced or income rises; it cannot make unaffordable necessities disappear
Use the printed $1,600 budget, then apply a $90 utility increase and a $120 periodic expense. Revise amounts, protect priority needs, and explain the trade-off
Budgets align net income, timing, needs, goals, periodic costs, and uncertainty. Safe banking requires comparing terms, verifying insurance, reconciling records, protecting credentials, and revising plans without shame
Work through all 12 questions. Open an answer only after you have written or explained your response.
$1,550
$50
Housing: fixed; food: variable; annual fee: periodic
Amount can change while the underlying need, such as food, medicine, utilities, or transport, remains necessary
$50 per month
Identify the gap, prioritize safety and necessities, revise what is feasible, and seek legitimate income, assistance, negotiation, or qualified support without shame
Checking supports frequent transactions; savings holds funds for future goals or reserves and may earn interest
Eligible deposits at a covered bank or credit union up to legal limits under its government-backed insurance system
Investment loss, scam transfers, stolen cash, uncovered institutions, or all payment-app balances; any two
Fees, minimum balance, interest, access, overdraft rules, transaction limits, insurance eligibility, or customer service; any four
Pending payments, holds, delayed deposits, or unrecorded purchases may not yet appear in the posted balance
Unique passwords, multifactor security, alerts, official channels, no shared codes, regular reconciliation, and prompt reporting; any three