What you will be able to do
calculate and explain opportunity cost; analyze gains and vulnerabilities from specialization and trade; compare economic systems as mixed institutional arrangements
How do scarcity, opportunity cost, specialization, trade, and institutions shape economic choices?
calculate and explain opportunity cost; analyze gains and vulnerabilities from specialization and trade; compare economic systems as mixed institutional arrangements
Describe the next-best alternative forgone when a class uses its final hour to rehearse instead of revising a report
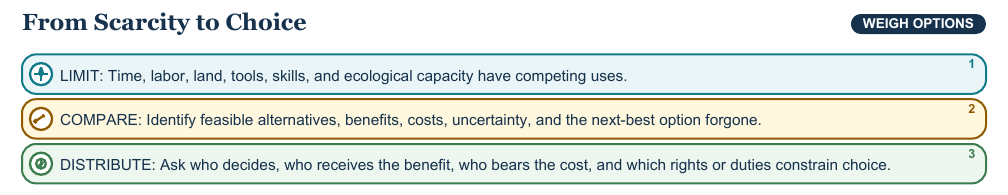
Scarcity means not every possible use can occur at once. It is not the same as poverty: a wealthy society still faces limited time, land, and ecological capacity, while poverty concerns inadequate access to resources and power. Opportunity cost is the value of the next-best alternative, not the sum of every rejected option. It depends on the decision maker and available choices. Specialization and division of labor can build skill, reduce switching time, and support tools designed for a task, raising productivity. They can also create repetitive work, dependency, job displacement, or vulnerability when one supplier fails. A productivity increase describes output per input; it does not by itself show wages, safety, product quality, environmental effects, or how gains are distributed
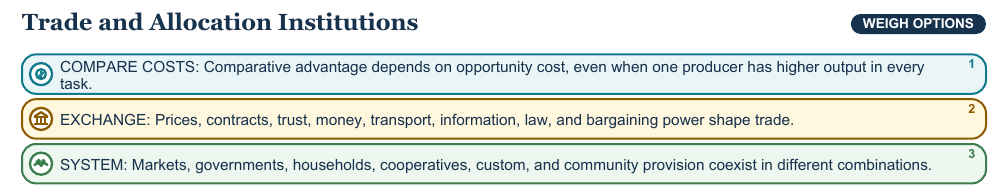
Comparative advantage explains why specialization and voluntary exchange can increase total output when producers have different opportunity costs. Gains are not automatic or equal. Transport costs, market power, unemployment during adjustment, unsafe labor, environmental damage, or coercion can change the result. Trade policy may pursue security, employment, revenue, rights, or resilience in addition to low price. Labels such as market, command, traditional, capitalist, or socialist summarize selected features but can hide variation. Every contemporary economy combines institutions: households provide unpaid care, governments tax and supply services, firms use internal plans, markets coordinate many exchanges, and communities share resources. Comparison should examine ownership, decision authority, incentives, protections, public goods, and distribution rather than placing whole countries on a simplistic single line
Opportunity cost belongs to a specific choice among feasible alternatives; different people may face different options and values
List each option, direct effects, next-best forgone choice, affected groups, uncertainty, and institutional rule before deciding
A price may omit unpaid care, pollution, public subsidy, labor risk, future depletion, or unequal bargaining power
Use a two-producer table to calculate opportunity costs, propose specialization, then test whether transport, fairness, resilience, or labor conditions change the recommendation
Scarcity creates choices whose opportunity costs depend on feasible alternatives. Specialization and trade can raise output, while institutions and power determine risks, distribution, and public responsibilities
Work through all 12 questions. Open an answer only after you have written or explained your response.
the value of the next-best alternative forgone
Scarcity is universal competition among limited uses; poverty is inadequate command over resources needed for well-being and is shaped by distribution and power
The value of revising the report, assuming it is the next-best feasible alternative
Practice and skill, reduced switching time, task-specific tools, coordination, or scale; any three
Benefits include skill or efficiency; risks include monotony, dependency, displacement, weak bargaining power, or system fragility
Wages, hours, safety, stability, distribution, and working conditions may not improve with output per input
Producing a good or service at a lower opportunity cost than another producer
Producer A, because A gives up only 2 baskets rather than 5
Money, contracts, trust, information, transport, law, measurement, credit, or enforcement; any three
Bargaining power, ownership, adjustment costs, market concentration, labor rules, transport, taxes, and externalities distribute effects differently
Markets, public provision, regulation, households, firms, cooperatives, and custom allocate different resources together
Ownership, decision authority, incentives, rights, public goods, distribution, environmental effects, stability, or innovation; any four