What you will be able to do
balance income and expenses; distinguish saving goal from emergency reserve; calculate simple credit repayment and identify risk
How can a fictional household budget income, save toward goals, and evaluate introductory credit?
balance income and expenses; distinguish saving goal from emergency reserve; calculate simple credit repayment and identify risk
Explain why monthly income and weekly expenses must be converted to the same time period before comparison
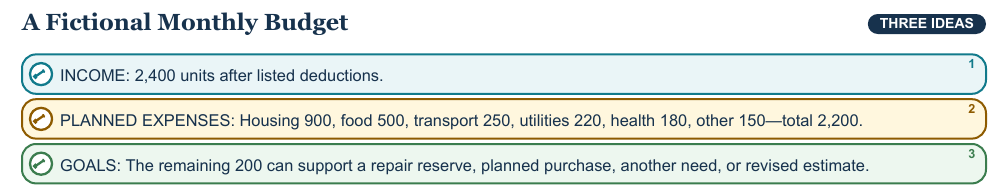
A budget places income, obligations, needs, wants, and saving goals in one time period. Fixed expenses are usually stable for the period; variable expenses change, but variable does not mean optional. Food, medicine, utilities, disability support, and transportation can be necessary while fluctuating. Estimated and actual spending should be compared. If transport costs rise by 80 units, the household must revise timing or another category, use available reserves, or seek assistance. There is no single correct response because housing, health, safety, contracts, and access differ. A balanced plan does not prove a household has enough resources
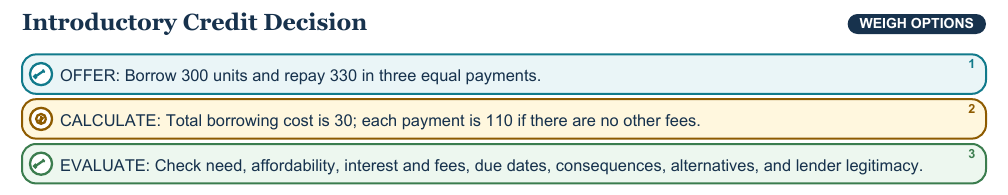
Credit may help handle timing, emergencies, education, housing, or useful purchases, but repayment reduces future flexibility. Interest compensates a lender and adds cost. Fees, late penalties, changing rates, collateral, and deceptive terms can increase risk beyond a simple example. Responsible evaluation compares total repayment, not only monthly payment. It also asks whether the expense is urgent, whether saving first is possible, and whether safer or lower-cost alternatives exist. People may lack access to fair credit because of structural inequality; using expensive credit is not proof of careless character
Convert all amounts to one time period, total them, protect required needs, and revise without moral judgment when reality differs
Calculate principal, total repayment, borrowing cost, number of payments, and due dates before discussing affordability
A lower payment may come from a longer term and larger total cost
Revise the fictional budget after an 80-unit increase, then compare the 300-for-330 offer with saving 100 units for three months
Budgets align income, needs, obligations, and goals. Saving moves resources to the future; credit moves future income to the present and requires total-cost and risk analysis
Work through all 10 questions. Open an answer only after you have written or explained your response.
2,200 units
200 units
Its amount changes even though food, health, transport, or utilities remain essential
Update the actual amount, retotal, protect required needs, and revise category or timing based on circumstances
Receiving money, goods, or services now under an agreement to repay later
30 units
110 units
Accept interest rate, fees, due dates, total repayment, term, late consequences, collateral, rate changes, or lender legitimacy; any three
It hides number of payments, term, fees, and total borrowing cost
Credit provides the item now but costs 30 and requires future payments; saving delays use but avoids this borrowing cost, if delay is safe and feasible