What you will be able to do
describe a market and price; predict a simple price pressure; evaluate an entrepreneurial idea using cost, need, and risk
How do buyers, sellers, prices, and entrepreneurs interact in markets?
describe a market and price; predict a simple price pressure; evaluate an entrepreneurial idea using cost, need, and risk
If many buyers want four available tickets, predict what pressure may occur on price without claiming it must change
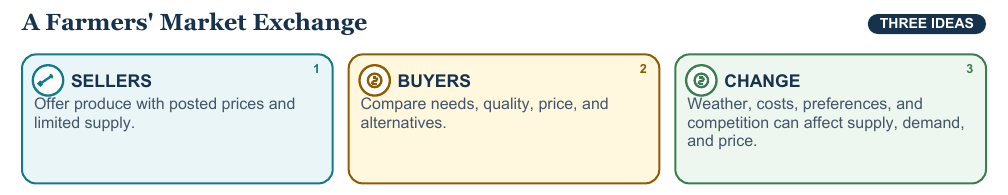
Markets can be physical or digital, private or public. Prices give information and shape choices, but they do not measure human worth or social importance. When demand rises while supply stays limited, upward price pressure may occur. When supply rises and demand stays similar, downward pressure may occur. Actual prices also reflect costs, contracts, laws, competition, and seller decisions. For example, a storm may reduce a farm’s strawberry supply while buyers still want fruit. Price may face upward pressure, yet a seller might keep a posted price, limit quantities, or honor contracts
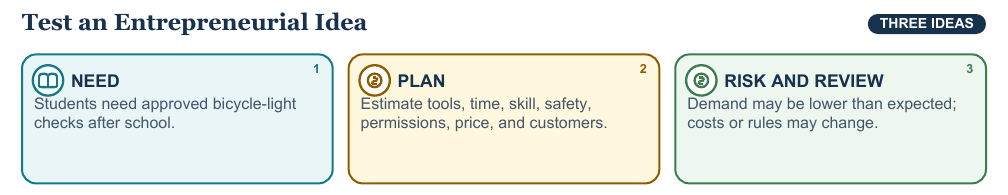
An entrepreneur identifies a possible need or want, organizes resources, and accepts uncertainty. Revenue is money received; profit remains only after costs. A viable idea must be lawful, safe, accessible, and honest. It may fail despite effort because demand, costs, competition, timing, or circumstances change. Failure is information, not proof of bad character. A demand survey can reveal interest without promising sales. The entrepreneur then estimates materials, labor, permits, accessibility, and time before deciding whether the expected revenue could cover costs
Simple supply-demand changes create likely pressure on price, not an automatic outcome in every real market
Keep numbers small and distinguish total money received from profit after costs
Price reflects market conditions and rules, not how important a good, service, worker, or person is
For an adult-approved fictional service, identify need, customers, two costs, price, risk, and a way to test demand without collecting money
Markets connect buyers and sellers. Supply, demand, costs, rules, and competition influence prices; entrepreneurs organize resources and accept risk without guaranteed profit
Work through all 10 questions. Open an answer only after you have written or explained your response.
An arrangement where buyers and sellers exchange goods or services
The amount asked or paid in an exchange
Upward price pressure
Accept production cost, rules, contracts, competition, market power, taxes, or seller decisions
A person who organizes resources and takes risk to offer a good or service
Revenue is all money received; profit is what remains after costs
Accept tools, replacement parts, time, training, space, insurance, or permissions
Demand, costs, competition, timing, or rules can differ from the plan
No; market price does not measure dignity or social importance
Accept an anonymous interest count, adult-run survey, observation, or small no-money prototype with permission