What you will be able to do
explain risk pooling, premium, deductible, coverage, and exclusions; distinguish saving, insurance, and investing; apply diversification, inflation, documentation, verification, and complaint steps to fictional cases
How do insurance, investing, diversification, contracts, and consumer protections address different forms of financial risk?
explain risk pooling, premium, deductible, coverage, and exclusions; distinguish saving, insurance, and investing; apply diversification, inflation, documentation, verification, and complaint steps to fictional cases
Explain why paying an insurance premium is not the same as placing money in a personal savings account for later withdrawal
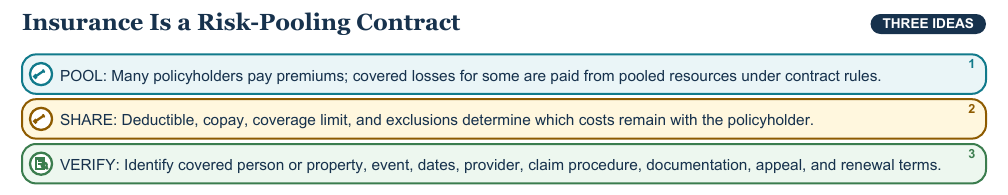
Insurance pools low-frequency or uncertain losses that could be difficult for one person to absorb. A premium buys contract coverage, not a guaranteed payout. A deductible is the covered amount paid before insurer contribution under the policy; exclusions and limits restrict what qualifies. Two policies with equal premiums can provide very different protection. Policy comparison starts with the risk being transferred, then examines coverage amount, deductible, exclusions, network or provider rules, claim process, financial strength, and total cost. A higher deductible may lower premium but requires greater emergency capacity. Insurance is different from saving because pooled premiums support covered claims across participants, and different from investing because its primary purpose is risk transfer rather than expected growth. Real choices require qualified adults and current jurisdiction-specific information
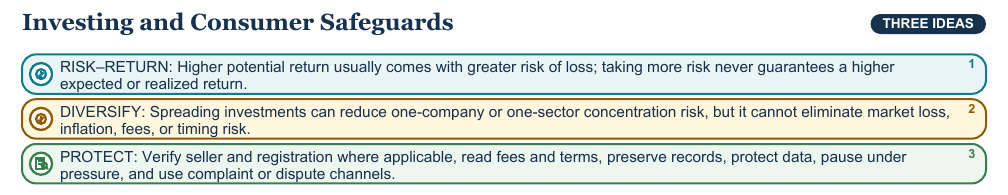
Saving commonly prioritizes near-term access and principal stability, while investing accepts price or credit risk for potential income or growth. Stocks represent ownership interests; bonds are debt obligations; pooled funds can hold many assets. Diversification reduces dependence on one outcome, but correlated losses can still occur. Inflation matters because a positive dollar return may buy less if prices rise faster. Fees, taxes, time horizon, liquidity, concentration, and fraud risk affect results. Past performance does not guarantee future return, and urgency or secrecy is a warning sign. Consumer protection begins before purchase: identify the seller, verify claims through independent official sources, read cancellation and warranty terms, and never send money or credentials under pressure. After a problem, document dates, receipts, messages, product details, and requested remedy; contact the seller through official channels and escalate to the appropriate regulator or dispute process with adult support
Name the exact covered risk, out-of-pocket share, limit, exception, claim evidence, and policy dates before comparing price
Saving handles access and reserves, insurance transfers specified loss, and investing pursues return with risk; do not compare them as interchangeable products
It can reduce concentration risk, but broad market decline, inflation, fees, and other losses can still affect the portfolio
Match an emergency reserve, catastrophic property loss, and a long-term goal to saving, insurance, or investing; justify risk, access, cost, and one consumer safeguard
Insurance pools specified risks under contract terms; investing accepts uncertainty for possible return; saving protects access and reserves. Consumer protection requires verification, diversification, records, privacy, and remedy channels
Work through all 12 questions. Open an answer only after you have written or explained your response.
transfer specified financial risk through a pooling contract
Premium is the price paid for coverage; deductible is the covered amount paid by the policyholder before insurer payment under the terms
They define events, items, causes, or conditions the contract does not cover
It may lower the premium while increasing the amount the policyholder must be ready to pay after a covered loss
Saving: access and reserves; insurance: transfer specified risk; investing: seek future return while accepting loss risk
An ownership interest in a company, with rights depending on the share type
A debt obligation in which the issuer promises payments under stated terms
It spreads exposure across holdings, but broad markets, shared factors, inflation, fees, or correlated losses can still reduce value
If prices rise faster than the return, purchasing power can fall despite a higher dollar balance
Guaranteed high return, pressure, secrecy, unregistered seller, unclear fees, credential requests, fake endorsements, or unverified contact; any four
Dates, receipts, contract or warranty, messages, screenshots, tracking, product details, and requested remedy
The seller benefits from acceptance and may omit risk; unrelated official or authoritative sources can confirm identity, terms, and regulation