What you will be able to do
distinguish principal, interest, APR, term, and payment; calculate simple fictional borrowing costs; identify collateral, default, compounding, fees, and deceptive or predatory warning signs
How can a borrower compare credit by total cost, timing, terms, rights, and risk rather than monthly payment alone?
distinguish principal, interest, APR, term, and payment; calculate simple fictional borrowing costs; identify collateral, default, compounding, fees, and deceptive or predatory warning signs
Explain why a smaller monthly payment can cost more overall when it extends repayment for many additional months
Credit can help manage timing, education, housing, transportation, business, or emergencies, but it commits future income. Principal is the amount borrowed; interest and fees are borrowing costs. For simple interest, interest equals principal × rate × time. Many real products use compounding or daily balance methods, so learners must follow the disclosed formula rather than applying simple interest automatically. APR helps compare annualized borrowing cost but does not replace total-dollar analysis, especially when terms and fees differ. A longer term often lowers each payment while increasing total interest. Installment credit follows a set schedule; revolving credit permits repeated borrowing and may have a changing balance and rate. A responsible comparison uses the same amount, repayment behavior, and time horizon and asks whether the payment fits a realistic budget
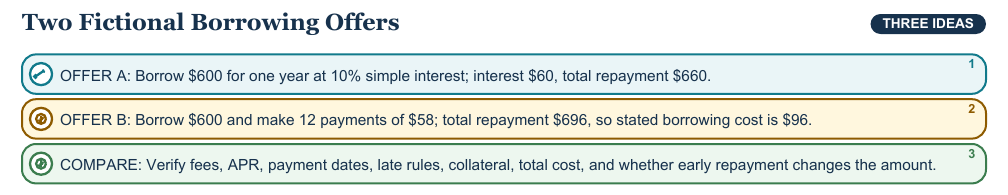
Secured credit uses collateral that may be taken after default under the contract and law; unsecured credit does not rely on a specified asset but can still involve collection and legal consequences. A cosigner becomes responsible for repayment, not merely a character reference. Missing a payment can trigger fees, higher rates, reporting, or default, so grace periods and hardship procedures matter. High-cost or predatory lending may exploit urgency, information gaps, repeat refinancing, unaffordable payments, or access to a bank account. The safe response to pressure is to pause, verify the provider independently, read the complete contract, compare alternatives, and consult a trusted adult or qualified nonprofit resource. Credit history systems record selected borrowing behavior but do not measure character, intelligence, or human worth. Students should use fictional cases and never disclose household debt or credit scores
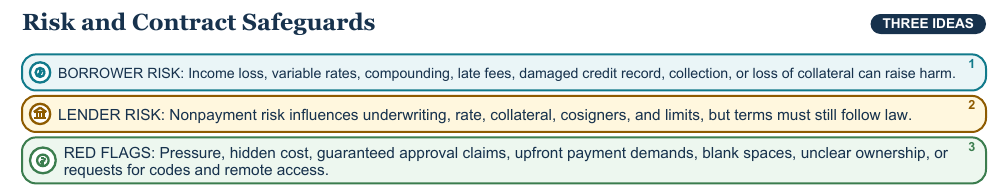
Write principal, rate, fees, term, payment, total repayment, collateral, late consequences, and assumptions on one page
Per day, per month, annual, introductory, due date, grace period, and term change the calculation; convert to one comparison horizon
A lender’s willingness to offer credit does not prove the payment fits the borrower’s budget or goals
Compare a simple-interest loan, a fee-based installment offer, and saving first. Calculate total dollars, test one missed payment, and identify a safest response
Credit trades present access for future obligations. Sound borrowing decisions compare total dollars, APR, term, formulas, collateral, budget fit, rights, alternatives, and warning signs without moralizing debt
Work through all 12 questions. Open an answer only after you have written or explained your response.
$60
$660
$696
$96
Total repayment, fees, term, rate, risk, and opportunity cost may be greater even if each payment is smaller
Installment credit has scheduled payments over a set term; revolving credit permits repeated borrowing up to a limit as the balance changes
Real credit may use simple, compound, daily-balance, variable-rate, or fee rules, producing different costs
Fees, term, payment dates, total repayment, collateral, late rules, grace period, variable rate, early repayment, or hardship options; any four
Accept an accurate three-part assessment tied to the fictional offer
A specified asset may be taken after default according to contract and law
Pressure, hidden terms, guaranteed approval, upfront payment, blank contract spaces, code requests, remote access, or unverified provider; any four
It records selected financial behavior shaped by access and circumstances; it does not measure ethics, intelligence, contribution, or dignity